

When comparing fractional property platforms in Dubai, we start with the rights attached to the investment, not the app or headline yield. The structure, costs, property and exit route all shape what an investor actually owns and may receive.
- Start with ownership: Establish whether you hold shares in an SPV or a registered interest in the property itself.
- Read the documents: Voting, distributions, transfer restrictions and operator-failure arrangements should be clear before you commit.
- Calculate net income: Rent can be reduced by vacancy, management, service charges, administration and other costs.
- Assess the asset separately: Location, tenant demand, condition and management matter regardless of how polished a platform looks.
- Understand liquidity: A resale depends on transfer rules and a buyer; an exit window follows the platform’s stated process.
- There is no universal best platform: Compare the legal structure, property exposure, reporting, costs and exit mechanics against your own needs.
How a fractional property investment works
In a fractional property investment, the investor contributes money towards a property interest arranged through a platform. The platform may select or present the property, collect investment funds and coordinate administration, while a separate legal entity may hold the asset; income distributions and sale proceeds then follow the investment documents and ownership structure.
Two common structures work differently. With an SPV, the company holds the property and the investor holds shares in that company; with registered direct co-ownership, the investor holds an interest in the property itself, supported by title records and co-ownership arrangements.
An SPV shareholder’s rights are corporate rights, set by company documents and the shareholder register. A direct co-owner’s rights arise from the property title and co-ownership agreement, but neither structure automatically gives an investor control over the whole property or a right to occupy it.
Fractional ownership is an investment interest, not a timeshare or a simple right to use a home. The legal documents determine how rent and sale proceeds are allocated, so we recommend understanding the structure before comparing projected income; our investment guide to Dubai property offers wider context on direct property decisions.
Check the ownership records and regulatory roles
Ask who legally owns the property and what record confirms your interest. For an SPV, look for the company’s share register and governing documents; for direct co-ownership, examine the title record and the agreement among co-owners.
Read the investment and company documents for voting rights, distribution rules, transfer restrictions, fees, dispute procedures and arrangements if the operator fails. These terms determine how decisions get made and what recourse investors have, not the platform’s branding.
| What to distinguish | What it covers | What to examine |
|---|---|---|
| DFSA | Financial services within the DIFC | The regulated activity and entity involved |
| Dubai Land Department | Property registration | The property title and registered ownership |
| RERA | Real estate activity in Dubai | The role and permissions relevant to the offer |
These roles are not interchangeable. A platform’s regulatory status does not, by itself, establish that an investor owns a property interest; compare the stated structure with the records and documents that evidence your rights.
For a direct property perspective, Off-plan properties in Dubai is a curated selection of projects assessed by M&M Real Estate for location, developer track record and growth potential. It helps illustrate asset selection, while a fractional offer still requires its own ownership and investor documents.
M&M Real Estate also provides property purchase guidance in Dubai, supporting investors and homebuyers from enquiry through handover, with a focus on off-plan apartments and waterfront projects. This direct-purchase guidance is a separate consideration from a platform’s SPV or co-ownership structure.
Compare income, appreciation and the costs that reduce returns
Headline rent is not net rental income. Establish how the platform allocates rent, when it distributes funds and whether vacancy, arrears, repairs or reserves reduce the amount investors receive.
Compare acquisition, platform administration, property management, service-charge and exit costs. Some charges apply to a particular transaction, while others can vary with the property’s use or the way an investor sells an interest.
Potential capital appreciation is a change in property value, not a promised return. Ask how a sale value would be assessed, which costs would be deducted and how the remaining proceeds would be divided among investors.
One illustrative worked example
For this hypothetical calculation, the amounts below are assumptions for illustration, not market data.
- Gross rent: AED 10,000
- AED 10,000 - AED 1,000 management = AED 9,000
- AED 9,000 - AED 1,500 service charges = AED 7,500
- AED 7,500 - AED 500 administration = AED 7,000 net rent
- A 10% share of AED 7,000 = AED 700
This calculation excludes acquisition and exit costs, which should be assessed separately. It also shows why a projected rental yield is not enough: the amount distributed depends on rent collected, deductions and the investor’s documented share.
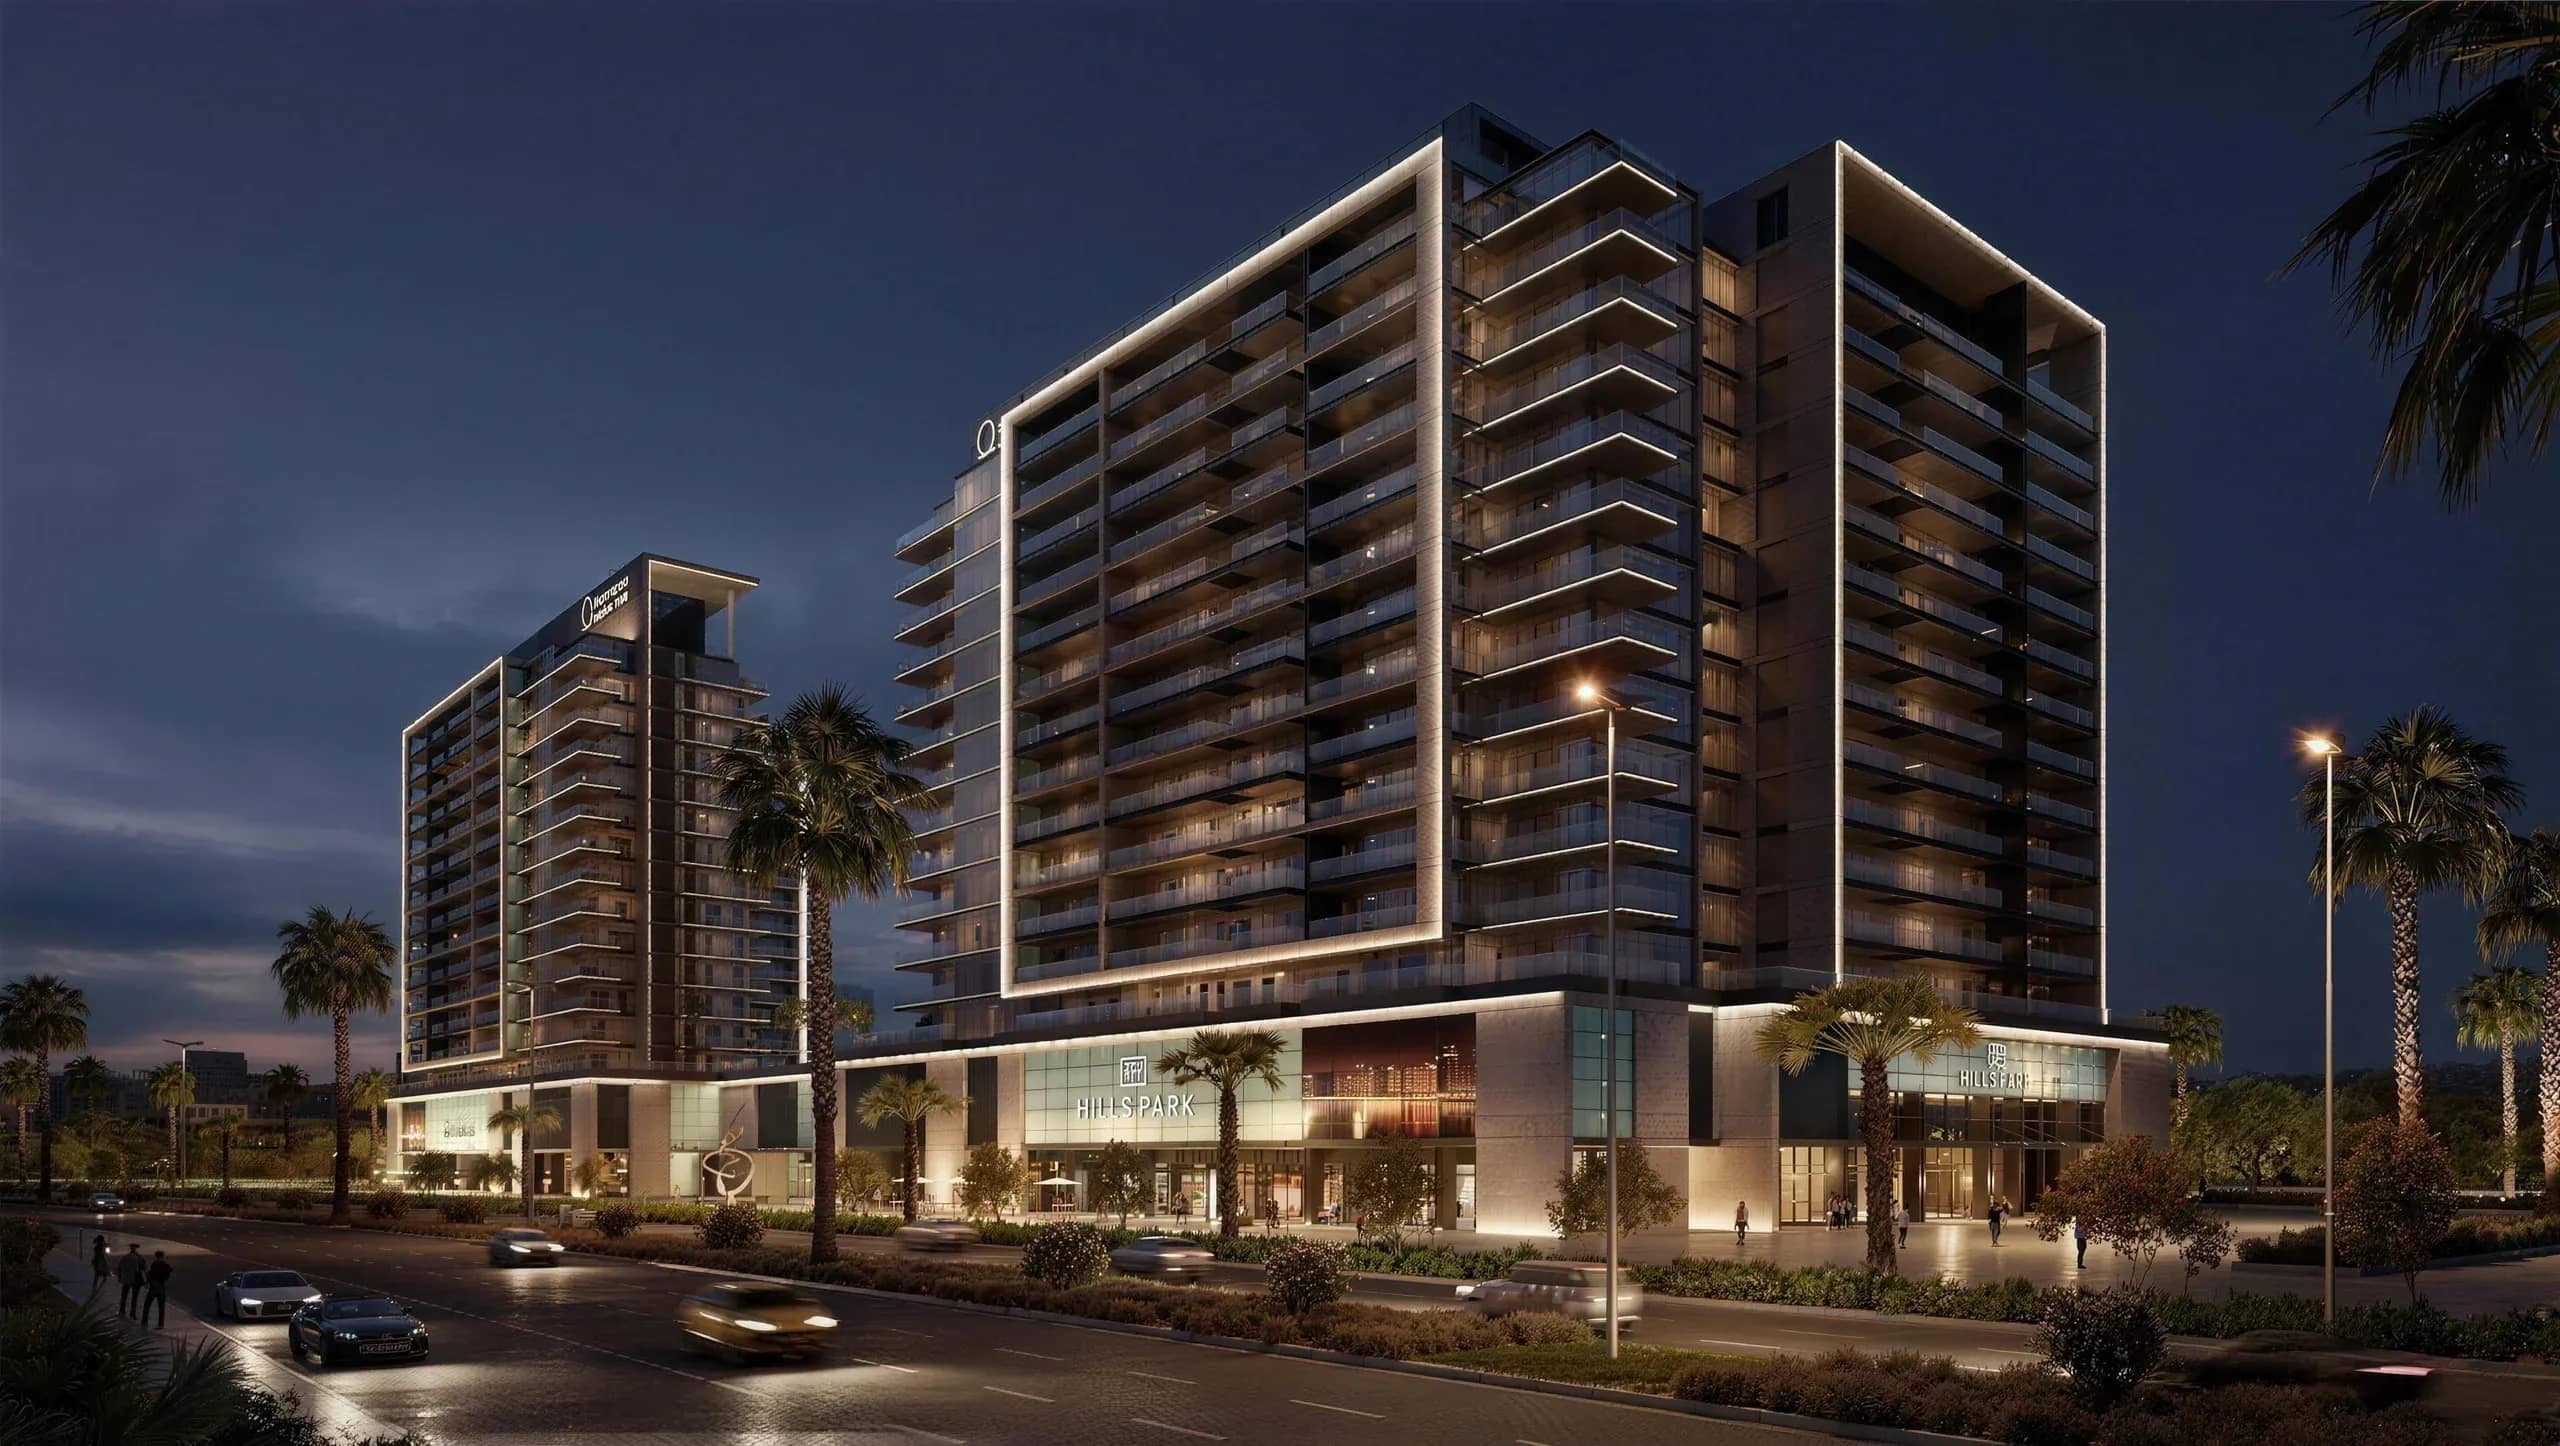
M&M’s 399 Hills Park project page illustrates how a specific property can be assessed separately from the costs and returns attached to a fractional platform interest.
Comparing a property’s own records with an investment offer helps keep the asset’s history separate from the platform’s fee and distribution terms.
What foreign buyers get wrong in Dubai off-plan, what each mistake costs, and exactly what to do instead.
Download free→Assess the property and the platform on separate merits
Analyse the property independently of the platform’s technology or presentation. Location, condition, intended tenant demand and the management plan affect the asset itself, while the platform determines how the investor accesses and oversees that asset.
Compare platforms on ownership-document clarity, fee disclosure, property selection, investor reporting, communications and decision-making. A clear breakdown of rent assumptions, expenses and sale value is more useful than a headline return without the workings behind it.
Test how an opportunity might respond to vacancy, lower rent or an unexpected repair. Projected rent and capital growth can change, so compare how each platform explains downside scenarios and who bears the related costs.
Our guide to Dubai investment areas and our locations page can help frame the asset-level questions. We also look at the developer’s role and record as part of property selection, rather than treating platform presentation as a substitute for due diligence.
Understand exit routes before investing
An exit window is a process set out by the platform, while a secondary-market resale depends on finding a buyer and meeting any transfer rules. Neither should be treated as an on-demand withdrawal facility.
Read how transfers work in practice: whether the operator must approve them, who can buy, how the interest is valued and which transaction costs apply. The investment documents should also explain what happens if no buyer comes forward or the property cannot be sold on the expected timetable.
Compare the stated holding period and sale process with your own cash needs. Liquidity depends on the asset, the legal structure and buyer availability, so the platform’s expected route to sale matters as much as its entry process.
A specific underlying property can be assessed separately from a platform’s exit terms; its location and identity do not establish how an investor could transfer a separate platform interest.
This infographic highlights key checks for comparing fractional property platforms in Dubai. Review fees, ownership structures, and available property options.
Test the risks and failure scenarios
At property level, vacancy, falling rents, repairs and service costs can reduce distributions or sale proceeds. Ask who manages the property, what reserves can cover and how investors receive updates when the asset underperforms.
Then consider operator failure. The documents should explain who would manage the property, maintain the property and investor records, and make decisions if the platform operator became insolvent.
Ask how the platform handles incomplete funding or a property that generates no rent. The offer documents should set out whether funds are returned, retained or used under specified conditions, and which investor votes or remedies apply.
Compare dispute processes and voting rights directly. Oversight by a regulator does not guarantee investment performance or repayment, so the legal documents remain central to understanding investor protections.
We bring the same no-noise approach to the failure case as to the projected return: identify who acts, what records remain available and how investors can raise a dispute. Our Dubai investment guides and resources provide further reading for property decisions.
Choose the structure that fits your circumstances
Compare the minimum investment, payment timing and all associated costs for each opportunity. Make sure the commitment fits your budget without relying on future rent distributions to meet other obligations.
For remote participation, establish whether non-residents can complete onboarding and investment steps from abroad. Find out which identity and payment records the process requires and keep copies of the documents that evidence your interest.
Choose only after comparing ownership rights, property exposure, reporting, costs and exit mechanics. Platform convenience can make administration easier, but it does not establish whether the investment suits your time horizon or tolerance for risk.
A project’s own record is separate from the terms and rights of a fractional investment.
We also keep property ownership and residency questions distinct. Our Dubai Golden Visa guide covers the residency topic, while the investment documents should explain the rights attached to the property interest itself.
Comparing fractional property platforms in Dubai starts with a practical question: what legal interest do you hold, and how do the documents protect and define it? From there, compare net income, asset quality, investor rights, operator-failure arrangements and the actual route to exit.
We believe a real investment decision needs clear ownership records and an honest view of costs and risk, not noise around a headline return. Choose the structure that fits your circumstances, and assess the property and platform on their separate merits.
Can a fractional property interest be held through a company rather than personally?
Yes, subject to the platform’s eligibility rules and the company’s governing documents. The company would hold the investment interest, and its own records should identify who controls or benefits from that holding.
How are disagreements between fractional investors resolved?
The investment and company documents should set out the applicable voting process, dispute procedure and route for escalation. Investors should understand whether a decision can be referred to mediation, arbitration or a court under the agreement.
Can an investor use a fractional property interest as collateral for a loan?
That depends on the legal structure and the lender’s willingness to accept the interest as security. Transfer restrictions, lender approval and the way the interest is recorded can all affect whether it can be pledged.
What should investors consider if they want their heirs to receive a fractional property interest?
Review how the company or co-ownership documents treat death, succession and the transfer of an interest. Investors should also consider whether their estate-planning documents and the relevant inheritance process recognise the same ownership structure.
What is the best fractional real estate platform?
The best fit is the platform whose terms suit your priorities and circumstances.
How should investors compare fractional property platforms?
Start by checking who holds the property, then compare the costs and transfer terms in each offer.


