
Investing in Dubai
from the UK.
Everything a British investor needs to know before committing capital to Dubai real estate. Tax implications, capital transfer, structures, Golden Visa, and the honest risks.
Why British investors are looking at Dubai.
The UK property market has become increasingly challenging for investors. Capital gains tax of 18% or 24% on residential property, stamp duty surcharges of up to 17% for additional properties and Section 24 mortgage interest relief restrictions are real structural pressures on British investor capital.
Dubai offers a legal, regulated alternative. No UAE capital gains tax on property and no UAE income tax on rental income, although UK residents still report both to HMRC. Full freehold ownership for foreigners. An average gross apartment yield of 5.53% (Global Property Guide, Q2 2026). Residency through property investment. An AED pegged to USD since 1997.
The British investor profile at M&M is typically someone who already has a UK property portfolio, is frustrated by diminishing returns and increasing tax burden, and wants to understand whether Dubai makes sense as a diversification vehicle, or as a primary investment strategy.
UK vs UAE:
the tax reality.
A direct comparison of the key tax implications for a British investor holding real estate in each jurisdiction. Always consult a qualified UK tax advisor before making any decisions.
| Tax / Obligation | 🇬🇧 United Kingdom | 🇦🇪 UAE / Dubai |
|---|---|---|
| Capital gains tax on property sale | 18% or 24% Significant | 0% Zero |
| Rental income tax | 20%, 40% or 45% (Income Tax) Progressive | 0% Zero |
| Stamp duty / transfer tax | Up to 17% (additional property) Surcharge | 4% DLD fee (one-time) One-time |
| Annual property tax | Council tax (£1,000 to £4,000+ a year) Annual cost | Service charge only Predictable |
| Inheritance tax | 40% above the £325,000 threshold Significant | No inheritance tax Zero |
| Non-dom status changes | Abolished from April 2025 Major change | Not applicable N/A |
This table is for informational purposes only and does not constitute tax advice. Tax treatment depends on individual circumstances, residency status, and changes in law. Always consult a qualified UK tax advisor (chartered accountant or tax specialist) before making any investment or residency decision.
Free investor report
Why London money is choosing Dubai.
What thousands of the highest-net-worth British residents are doing right now, the forces pushing them, and what Dubai actually offers in 2026. 27 pages, free.
How British investors buy in Dubai.
Five steps from first conversation to ownership. No residency requirement, no local partner, no complicated structure needed for most investors.
objective
correctly
to UAE
Oqood registration
HMRC
Moving money from the UK to Dubai.
Transferring capital from the UK to UAE is a standard international wire transfer. There is no restriction on moving sterling to UAE, the UK has no capital controls.
Most UK banks process international wires to UAE banks without issue. You will need to declare the purpose of the transfer (property purchase) and provide the payment details (for off-plan, the project’s escrow account). Your bank may ask for source of funds documentation and the SPA.
Many clients prefer to use FX specialists for better exchange rates on the GBP to AED conversion. The AED is pegged to USD at 3.67, so the real conversion is GBP → USD → AED. Even small rate improvements on large transfers can save thousands.
Golden Visa and residency options.
A purchase of AED 2M or more in your own name can qualify you for the UAE Golden Visa, a renewable permit DLD issues for 10 years (u.ae lists 5 years for real estate investors, so we confirm the term case by case), providing a strategic international base.
For UK investors, the Golden Visa provides UAE residency without requiring you to give up your UK status. You can hold both. This gives you access to UAE banking, the ability to sponsor family members, and a base in one of the world’s most connected cities.
Important: UAE residency alone does not automatically change your UK tax status. You must meet HMRC’s Statutory Residence Test (SRT) criteria to become UK non-resident. This requires careful planning with a qualified UK tax advisor.
We advise British investors with clarity.
Our advisory team understands the specific legal, fiscal, and regulatory context of the British investor. We work alongside UK-qualified solicitors and accountants to ensure your Dubai investment is correctly structured from day one.
Buying Property in Dubai From the UK: Tax, Financing, Process
Reviewed by Juan Mejia · 13 October 2026
UK investors · Dubai property
If you remain UK tax resident, Dubai rental income and a gain on a Dubai property sale can have UK tax consequences. Leaving the UK changes the residence analysis, while ownership still needs to be considered in your estate plan. M&M Real Estate advises UK-based investors on Dubai opportunities, investment analysis and ownership structure, then supports the purchase and rental setup.
Speak with an M&M advisor
What HMRC expects while you own, sell or leave
This is general information, not tax or legal advice. UK tax residents generally need to consider overseas rental income and property gains under UK tax rules.
While you hold the property
Keep a clear record of Dubai rent received, management costs, maintenance, service charges and periods without a tenant. The records help establish the rental result to report in the UK and support the figures used in your tax return.
M&M supports investors from initial analysis through purchase and rental setup. For UK-specific investment context, see the Dubai investment guide for UK investors.
When you sell
A sale can create a UK tax reporting question if you are UK tax resident. Retain the purchase and sale documents, transaction costs and evidence of qualifying improvement expenditure so an adviser can calculate the position using the relevant facts.
Review the exit plan before committing to a unit. The expected sale route, ownership structure and likely holding period belong in the investment analysis.
If you leave the UK
Moving abroad does not itself settle the tax treatment of income or a later sale. Your residence position, timing of departure and any subsequent return can affect the analysis, so a UK tax adviser can assess the relevant tax years and reporting obligations.
For estate planning
Dubai property ownership should form part of cross-border succession planning. The title holder and ownership structure affect how the asset is dealt with, so include the property in discussions with your UK and UAE legal advisers before purchase.
Choose the right Dubai property and ownership route
On Palm Jumeirah, buyers of any nationality can hold full title to freehold property, resell it or pass it on without restriction, as described in the Palm Jumeirah property guide. Freehold gives the buyer ownership of the property; leasehold is a different title arrangement. Check the specific area and title documents as part of legal due diligence.
For an investment, compare the building, developer, location, expected tenant profile and full ownership costs. A rental estimate should account for vacancy, management, maintenance and service charges, not just the advertised rent. M&M’s recommendations draw on transaction trends, developer history, rental-yield projections, capital-growth analysis and comparable market rates.
For an off-plan shortlist, investors comparing it with a completed home can review M&M’s curated off-plan properties in Dubai and Palm Jumeirah properties. These routes have different completion, payment and rental timelines, so assess the investment against your own cash flow and holding plan.
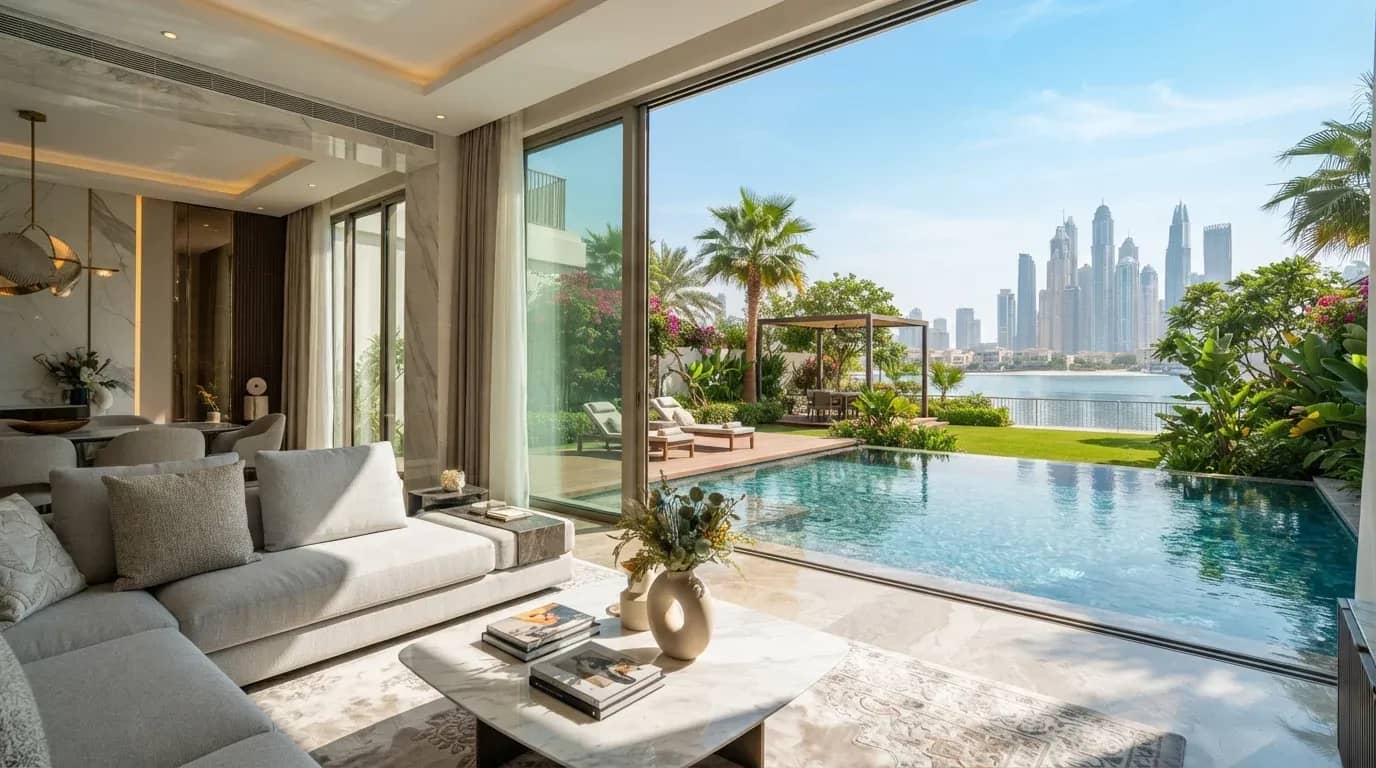
Financing, currency and due diligence
Compare a non-resident mortgage, available cash and a developer payment plan against the timing of each payment. Mortgage eligibility and terms are set by the lender, while an off-plan schedule links payments to the contract and project stages. Payment plans, escrow accounts, Oqood registration and buyer protections are covered in M&M’s Dubai off-plan guide.
Sterling-to-dirham exchange movements can change the sterling cost of a purchase or instalment. Build the currency conversion into the cash-flow plan before signing, and retain transfer records and source-of-funds documents for the transaction file.
Before committing, have the contract and ownership documents reviewed by an independent legal adviser. Check the seller’s authority, title details, outstanding charges, payment instructions and completion registration. For off-plan property, examine the developer, project registration, escrow arrangements, construction-linked payment terms, handover provisions and the contract’s delay and cancellation clauses.
In a ready-property purchase, the MOU and transfer documents set out the agreed transaction terms. In an off-plan purchase, review the sale and purchase agreement and registration details. M&M guides clients through the purchase stages.
What thousands of high-net-worth British residents are doing right now, the forces pushing them, and what Dubai offers in 2026.
Download free→Review the investment before signing
M&M’s advisory starts with your investment objective and analysis, then considers the ownership structure and suitable Dubai opportunities. Share your situation with an advisor to discuss a property shortlist, tax questions for your professional advisers and the purchase plan.
Talk to an M&M advisor
UK-to-Dubai service area and client support
This is a cross-border service area: the investor may be based in the UK, while the property search, purchase and rental setup are in Dubai. M&M supports international investors through the purchase process. Dubai opportunities include off-plan and waterfront property, with locations such as Dubai Islands and Palm Jumeirah.
Rather than relying on a return promise, ask for the assumptions behind the project assessment, including costs, rental demand, timing and exit options. Explore current Dubai property investment cases to see how M&M assesses individual projects.
Questions UK buyers ask about Dubai property
What do UK residents report to HMRC on Dubai rental income?
Use rent and expense records to discuss the taxable amount with a UK tax adviser.
Does selling a Dubai property affect UK tax?
Keep the purchase price, documented improvement costs and sale proceeds together for your adviser.
Can a UK buyer complete a Dubai purchase without travelling?
A UK-based buyer can arrange much of the purchase remotely through advisers and the required transaction documents. The process still needs appropriate identity, funds and ownership documentation, alongside registration and completion steps in Dubai.
Can a UK non-resident get a mortgage from a UAE bank?
Some UAE lenders consider non-resident mortgage applications, with eligibility and terms set by the bank. Compare the lender’s requirements and repayment terms with the property’s payment schedule before committing.
How do ready and off-plan property purchases differ?
Compare the ready property’s transfer timing with the off-plan contract’s payment milestones and handover terms before choosing.
What recurring costs should a Dubai property owner budget for?
Set a net-income estimate only after collecting the unit’s actual recurring charges and rental assumptions.
Plan your Dubai purchase from the UK
Bring your investment goals, expected holding period and funding plan to a conversation with M&M. An advisor can discuss suitable Dubai opportunities and the analysis to complete before you commit.
Speak with an M&M advisor
Figures are past data; this article is general information, not tax, legal or financial advice, and returns are not guaranteed.