

A Dubai property portfolio should be built around your investment goals, not a collection of addresses that happen to look appealing. We start with the role each asset must play: generating rental income, supporting capital growth, or preserving flexibility for a future sale.
Key Takeaways
| Decision | What to focus on |
|---|---|
| Set your goals | Decide how much weight to give cash flow, capital appreciation and liquidity before comparing properties. |
| Compare rental returns | Look beyond gross yield and account for service charges, maintenance, management and vacancy when assessing net yield. |
| Choose communities carefully | Assess tenant demand, transport, services, competing supply and resale appeal at the community level. |
| Review off-plan risk | Examine project progress, developer delivery history, payment obligations and likely appeal to end users. |
| Plan for ownership costs | Include transaction costs, recurring expenses, financing terms and your tax residence in your return assessment. |
| Keep the portfolio adaptable | Track occupancy, net cash flow, concentration and exit liquidity, then rebalance when your goals or the investment case changes. |
For a starting point, use our developer directory to compare delivery histories, browse Dubai off-plan opportunities with a clear investment purpose, and refer to our property investment resources as you build your shortlist.
Give Every Property a Clear Role
First, write down what you need your investments to do. A rental unit may be there to provide recurring income, while a property in an expanding community may offer a longer-term growth case with less immediate cash flow.
These roles are not interchangeable. A premium home can attract a different tenant and buyer profile from a smaller apartment, while an off-plan purchase may tie up capital before it produces rent.
We look at the portfolio as a whole, then assess each property on its own merits. That helps avoid the familiar mistake of buying another unit simply because the first one performed well.
If you are considering a second investment property in Dubai, test whether it adds a different source of demand, property type or exit route. To scale a property portfolio in Dubai, build from a deliberate allocation rather than accumulating similar units in the same place.
A diversified Dubai portfolio has a reason for each asset, and a clear plan for what happens if that asset underperforms.
Choose Communities for Demand and Resale Appeal
A suitable rental community gives tenants practical reasons to stay: access to employment, transport, shops, schools or leisure facilities that match the people you want to attract. For resale, ask whether the same features will continue to matter to future buyers.
Compare the property with nearby alternatives, not just the project brochure. Consider the condition of the building, the quality of shared facilities, competing units, access routes and the amount of new supply that could reach the market before you plan to sell.
Compare communities by considering how the unit’s size and layout fit the likely tenant; an attractive location cannot compensate for a poor match between the home and its intended market.
Dubai Marina and Jumeirah Village Circle illustrate why community choice needs to be assessed at a local level. Compare their access, housing mix and likely tenant profiles against your own priorities; no single area suits every strategy.
Compare Rental Yield With Real Operating Costs
Gross yield compares the annual rent with the property’s purchase price. Net yield gives a more useful view of operating performance because it accounts for recurring costs before comparing the income with the total amount invested.
To estimate net operating income, start with rent you expect to collect and subtract service charges, maintenance, property management, insurance where relevant, and an allowance for vacancy and leasing costs. If you have a mortgage, review financing separately so that operating performance and financing costs do not get mixed together.
Use comparable rental properties with similar layouts, condition and location when estimating rent. Our rental analysis also needs to account for lease terms and RERA requirements, since a headline rent does not tell you how stable the income will be.
We explain the difference between asking rent and a more grounded income assessment in our rental and yield analysis. Compare each property on its likely net cash flow, not on an advertised gross yield alone.
Foreign capital is hesitating. The 3.9 million people inside the UAE have not. The asymmetry that defines 2026, and what it tells you to do about it.
Download free→Balance Income, Growth and Different Asset Types
Income-focused homes can support cash flow, while growth-focused properties depend more heavily on future demand, infrastructure and resale appeal. Premium assets may serve a distinct buyer or tenant segment, but their price alone does not make them a sound investment.
Build a mix that reflects your available capital and tolerance for delayed income. A ready home can provide a clearer view of current rent and building condition, while an off-plan property exposes you to construction, handover and future supply risks before leasing can begin.
Keep concentration under control. A portfolio made up of similar apartments in one community can be exposed to the same vacancy pressures, service-charge changes and resale competition.
Use the infographic as a prompt for comparing property choices. Then apply the same criteria to each candidate, rather than letting a striking feature or a payment structure dictate the decision.
Use these comparison factors to assess how each property fits your investment goals and portfolio.
Assess Off-Plan Projects Before Committing
An off-plan property can suit an investor who has a clear time horizon and does not need immediate rental income. The payment plan is only one part of the decision; assess the full purchase obligation, delivery schedule, project location and likely demand from future residents.
Our due diligence starts with the developer’s delivery record and the project’s progress. We also examine the building specification, unit layout, surrounding infrastructure, end-user appeal and comparable rents and sales.
Before committing, make sure you understand the reservation and sale documents, payment milestones, ownership arrangements and the process for handling delays. A branded launch or an instalment schedule cannot replace evidence that the property fits your investment case.
Read our Off-plan guide alongside our broader investment guide for Dubai property. We use both ready and off-plan comparisons to bring the risks into the open before a client commits.
Budget for Acquisition, Ownership and Overseas Factors
Estimate the total cost of buying and holding a property, not only its advertised price. Consider DLD registration, any agency and conveyancing fees, mortgage-related costs, service charges, maintenance, furnishing and leasing expenses where they apply.
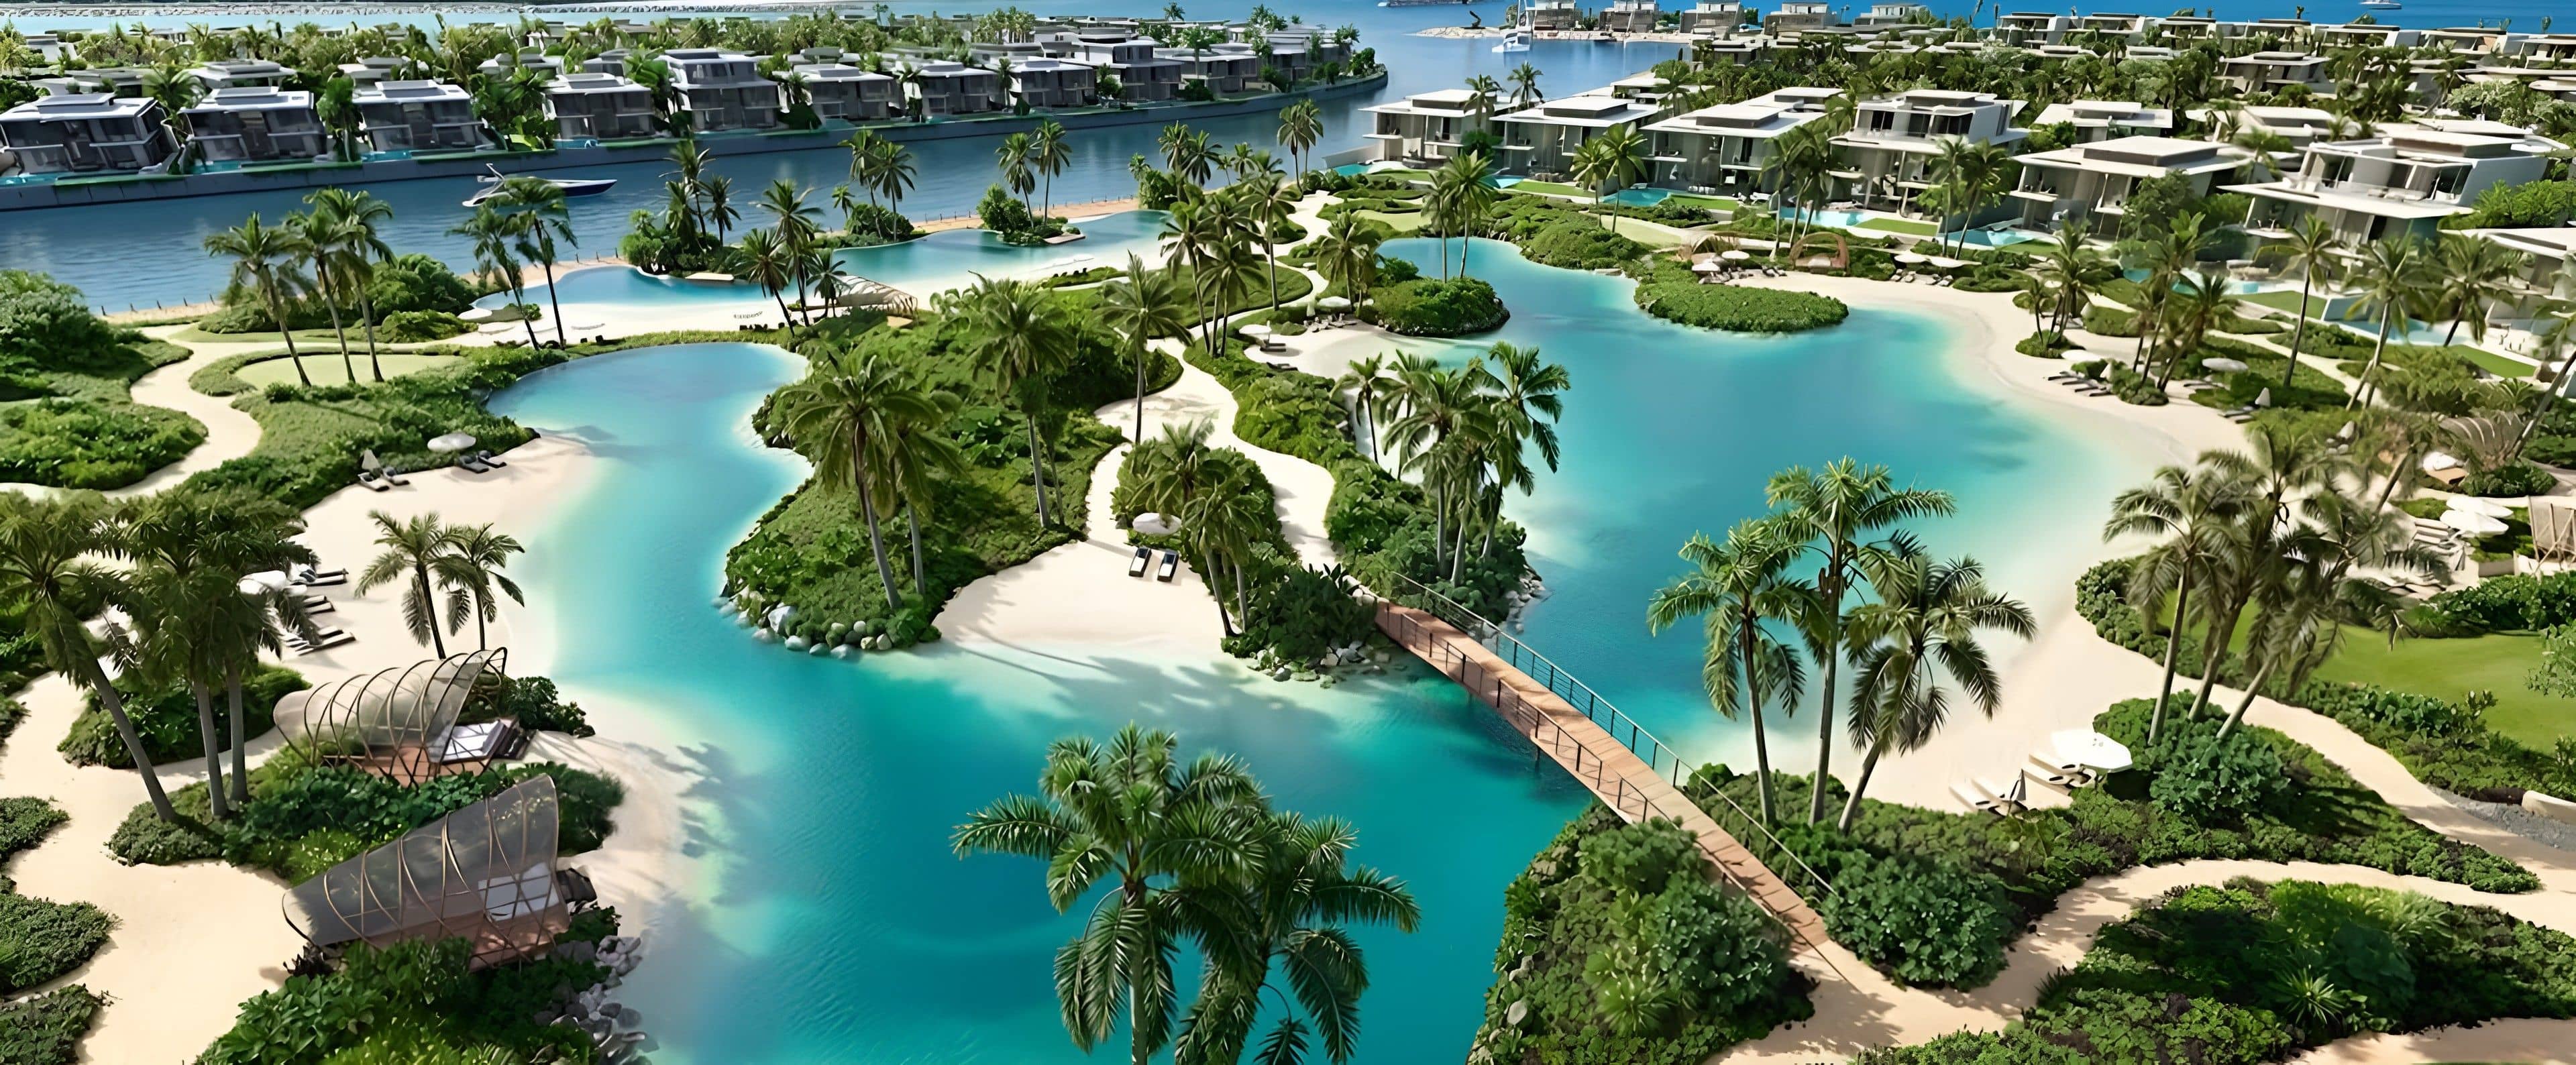
For one worked illustration, the M&M Bay Estate investment case lists a starting price of AED 5.9 million. Using the 4% DLD transfer fee described in our tax guide: AED 5,900,000 × 0.04 = AED 236,000; AED 5,900,000 + AED 236,000 = AED 6,136,000 before other purchase costs.
For an overseas owner, currency movements can change the value of rent and sale proceeds when converted into your home currency. Financing terms also affect cash flow, so assess repayment obligations alongside the property’s income rather than treating borrowing as a separate issue.
Your tax residence can affect the real return from property ownership and sale. Review the relevant rules with a qualified adviser in your country of residence, and consider residency plans separately from the investment merits of the asset.
Our discussion of tax considerations for property investors helps frame the questions to take to your adviser. If property ownership connects to a UAE residency plan, read our guidance on the Dubai Golden Visa as a separate part of your decision.
Monitor Performance and Rebalance With a Plan
Review your portfolio against a small set of useful measures: net cash flow, occupancy rate, tenant turnover, costs against budget, concentration by community and property type, and the ease of selling each asset. Compare actual performance with the assumptions you used when you bought.
Stress-test the plan for delayed handovers, weaker rents, longer vacancies and softer resale demand. Cash reserves give you room to meet ownership costs and financing obligations without being forced into a sale at the wrong time.
Rebalance when the original investment case changes, a holding creates too much concentration, or your own goals shift. Before selling, account for transaction costs and the time horizon you set at purchase; selling too soon can erode returns even when the headline sale price looks attractive.
There is no single answer to whether Dubai property prices are dropping that can guide every purchase. Assess completed transactions and current competition for the specific property type and community, then decide whether the price makes sense for your intended holding period.
See also: Locations.
A considered Dubai real estate portfolio balances income, growth and liquidity while accounting for costs, tenant demand and the risks attached to each asset. We build from real investor goals, test the assumptions, and keep the investment case clear from selection through to a future sale.
Can I hold Dubai property through a company?
A company structure can affect ownership administration, financing and tax treatment in more than one jurisdiction. Get legal and tax advice on the proposed structure before you make an offer, and compare it with direct ownership against your own objectives.
Does currency hedging make sense for an overseas property owner?
It depends on how much of your income, debt and future spending sits in each currency. Map the rent, financing and likely sale proceeds against your home-currency needs before deciding whether a currency strategy is appropriate.
Should I furnish a Dubai rental property?
Choose furnishings to suit the tenant group and lease strategy you expect to serve. Compare the likely rent and tenant appeal with the purchase, replacement and maintenance costs of the furnishings before fitting out the unit.
How do service charges affect a property’s rental yield?
Service charges reduce the income left after operating costs, so they can make a high gross yield less attractive on a net basis. Review what the charges cover and compare them with the building’s facilities, maintenance needs and expected rent.
Can commercial property fit into a residential portfolio?
Commercial space can add a different tenant base, but its income depends on business demand, lease terms, fit-out requirements and the time needed to secure a new occupier. Assess those factors and the likely exit market before treating an office as a diversification tool.
How should I compare a ready home with an off-plan home as an overseas investor?
A ready property lets you assess the completed building, current condition and rental market before purchase. An off-plan investment requires more attention to construction progress, handover timing and the developer’s record, so match the choice to your appetite for waiting and your need for near-term income.


