

For an international investor, the off plan vs ready property in Dubai decision in 2026 has no universal winner. A ready home requires more cash upfront but can earn rent sooner; off-plan payments are staged, but income usually waits until handover, delivery timing and the eventual valuation remain uncertain, and borrowing is more limited while the property is still off-plan. Rather than pick a winner, compare how each route affects your cash, income, risk and leverage.
What changes between off-plan and ready property?
A ready property exists and can be inspected before purchase. If it is vacant or has a tenancy that suits your plans, you can begin renting it after completion. You can also assess its condition and the surrounding neighbourhood directly.
With an off-plan purchase, you buy a home that is still being built. Payments follow the agreed schedule, and rental income generally starts only after handover and any preparation for tenants. Savills’ Q2 2026 Dubai residential market report describes delivery timelines stretching to roughly three to four years, so the wait can form a significant part of your investment plan. Read the Savills Q2 2026 report.
Both routes carry a 4% Dubai Land Department (DLD) fee. The DLD sale-registration schedule applies to ready sales, while an off-plan purchase is registered through Oqood at 4% plus AED 20, according to the DLD sale-registration service and its initial-sale registration service. Build the fee into your cash plan whichever route you choose.
The two investment cases
Case one: a ready one-bedroom in Jumeirah Village Circle
A ready apartment in Jumeirah Village Circle (JVC) is the more direct route if your aim is to start earning rent soon. You can inspect the unit, review its tenancy status and compare it with other homes in the area before committing. Your cash is tied up earlier, but the property can begin producing income once the purchase is complete and it is ready to let.
For area context, see M&M Real Estate’s Jumeirah Village Circle guide. Any rental estimate should be treated as a forecast, not a promise: actual income depends on the unit, its condition, tenancy, costs and the rent achieved.
Case two: an off-plan one-bedroom at Arancia, The Yards
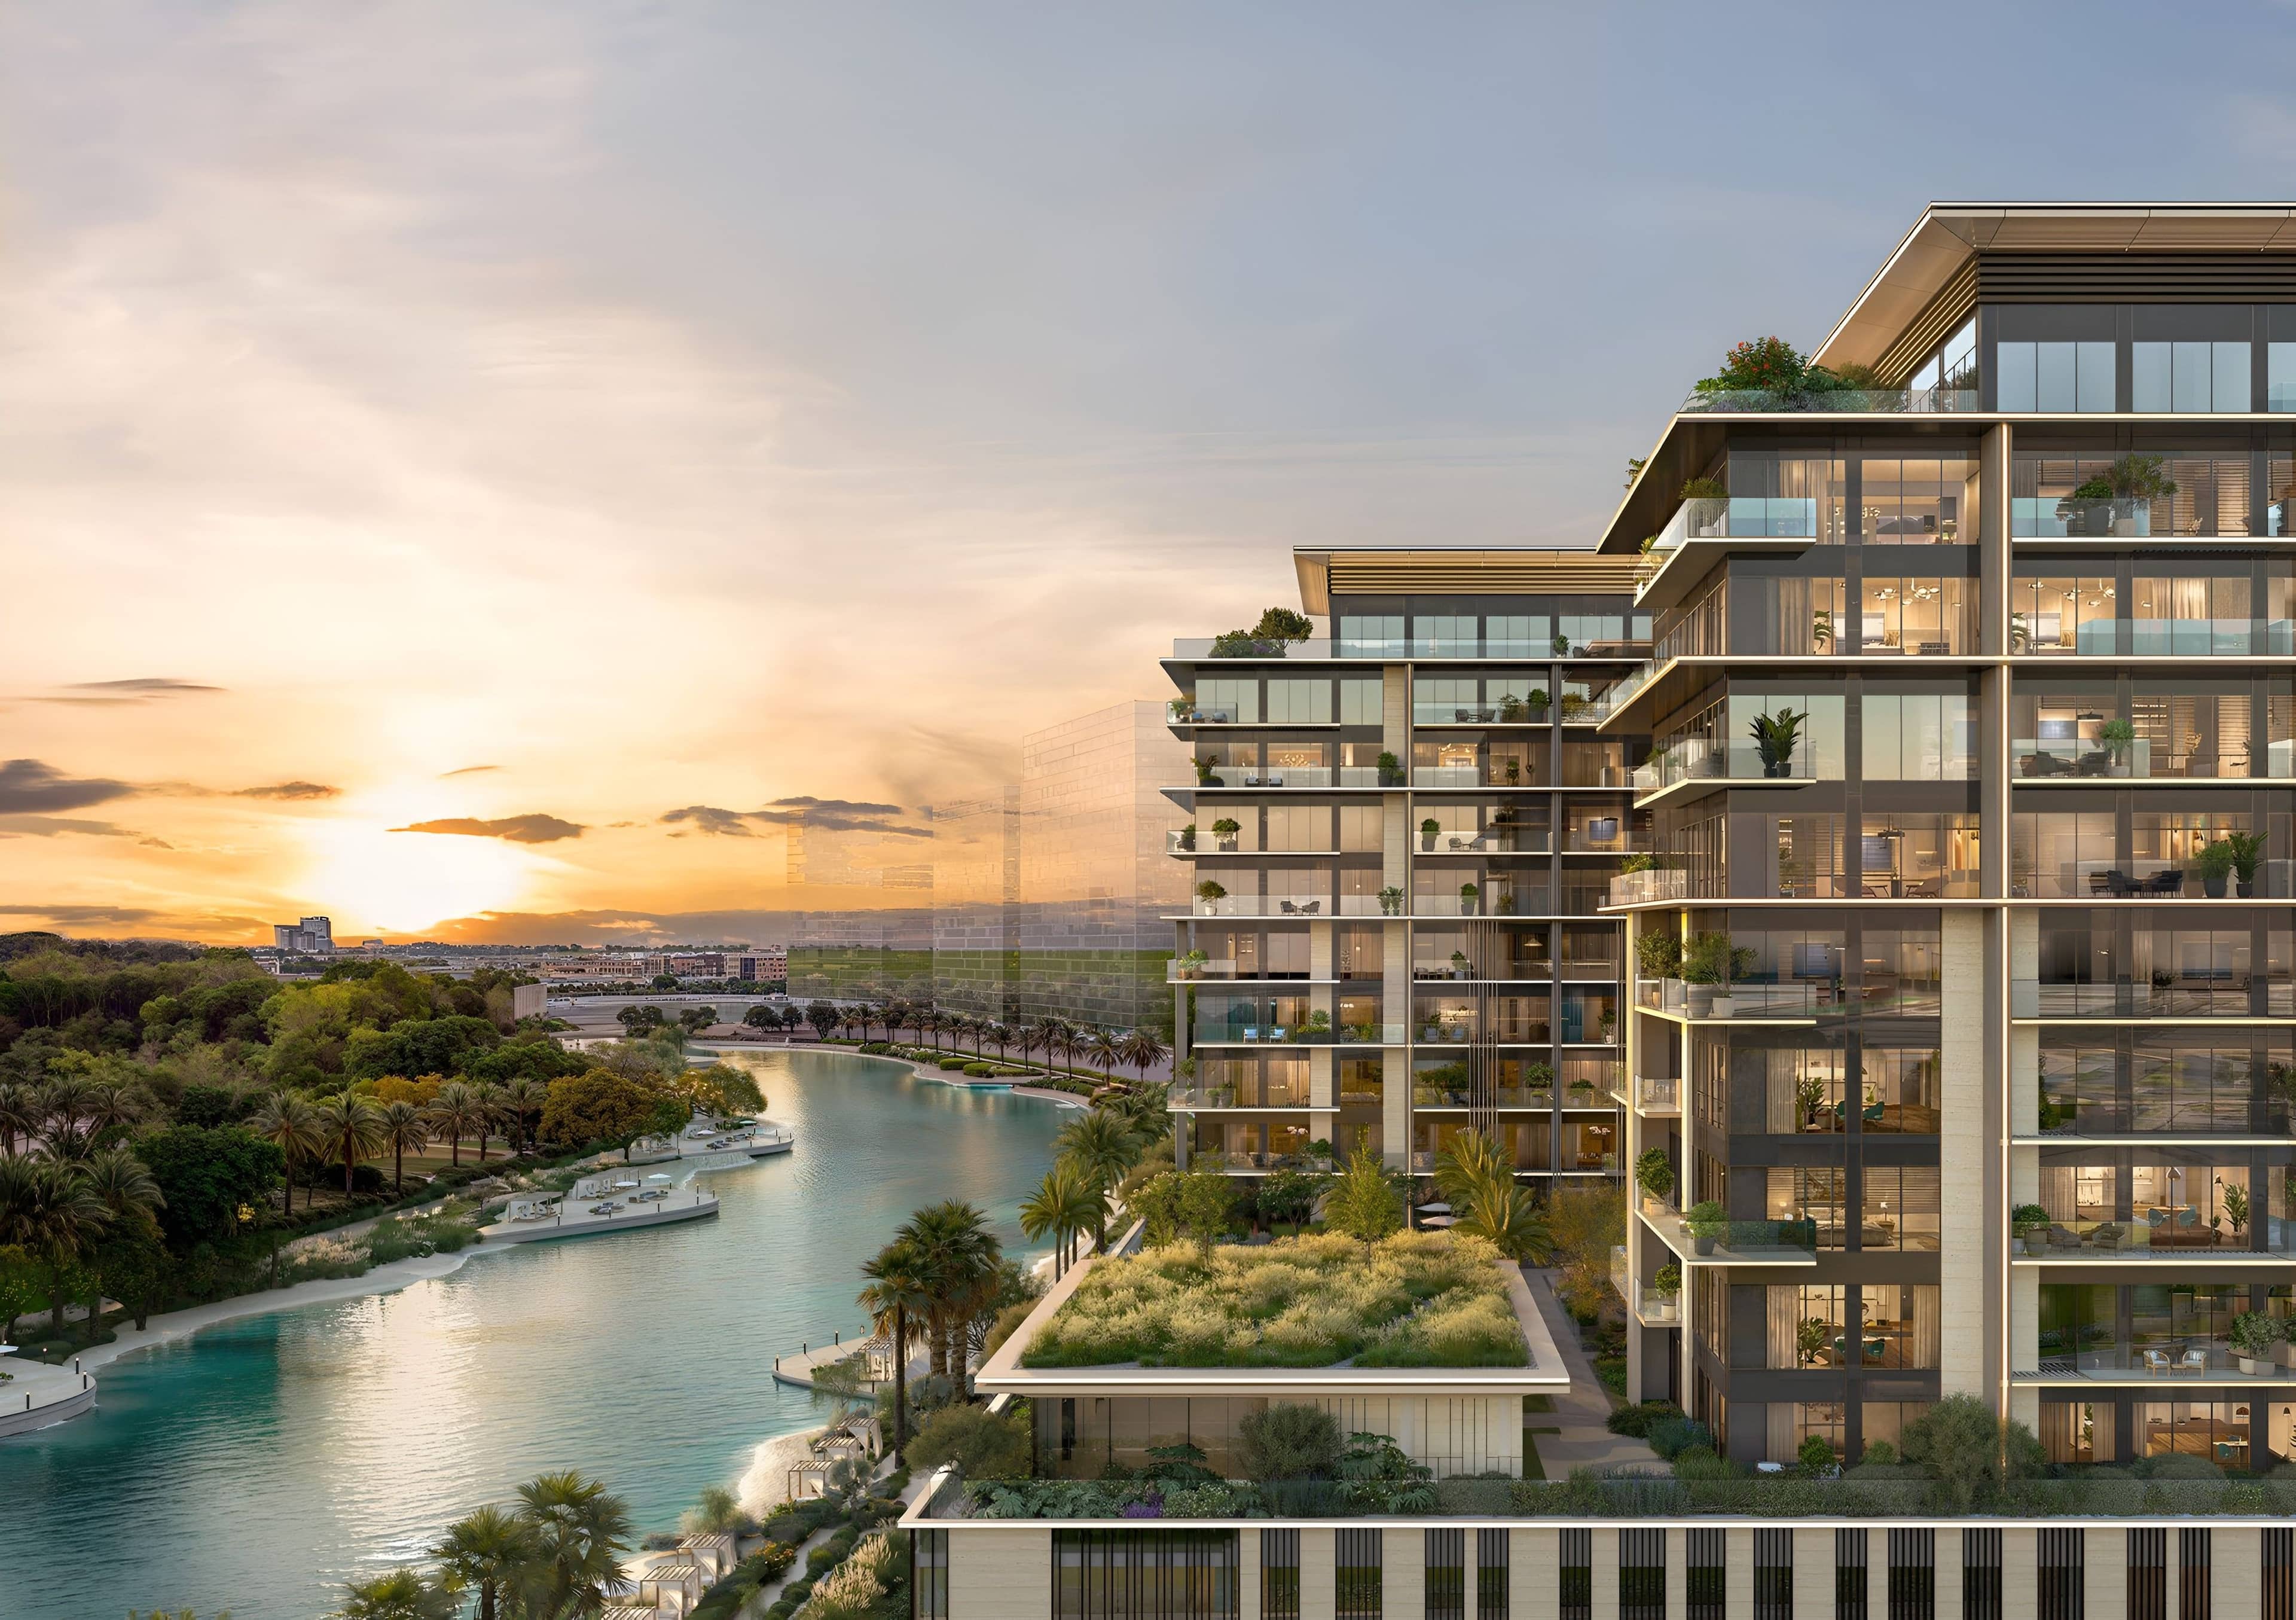
An off-plan home such as the one-bedroom in M&M’s Arancia, The Yards case uses a staged payment plan. This can leave more of your capital uncommitted before handover, but it does not produce rent during construction. Your eventual financing also depends on the lender’s assessment and the property’s value when you seek a loan.
Staged payments do not remove the need to check the project, developer, sale and purchase agreement (SPA), escrow arrangements and the terms that apply if payments stop. M&M’s Dubai off-plan buying guide sets out points to review before booking. For a separate example of a project case, see Everly Place, and check the specific unit’s current payment schedule before relying on it.
Four questions to ask before choosing
How much cash must I commit, and when?
A ready purchase usually calls for a larger amount of capital at the start, since the buyer completes the sale upfront or arranges finance at purchase. Off-plan payments are spread across the construction period according to the contract, but the schedule still creates binding payment obligations. Include purchase fees and any finance costs in your comparison, not just the advertised price.
When can the property generate income?
A ready property may earn rent soon after completion if it is suitable and available to let. With an off-plan property, rent normally begins only after delivery, handover and preparation for occupation. That waiting period has an opportunity cost: money committed to the off-plan unit is not producing rental income from that home during construction.
As a market reference, Global Property Guide reported gross yields of 5.53% for Dubai and 6.86% for a JVC one-bedroom in Q2 2026. These are gross figures, not net income after costs, and they do not predict the return on a particular apartment. For more context on the difference, read M&M’s guide to Dubai property rentals and yields.
Which risks should I assess?
For a ready home, check the unit’s condition, title and tenancy details, as well as service charges and comparable rents. A viewing can help you assess the property as it stands, but it does not guarantee future rental income or resale value.
For off-plan, review the project’s registration, construction progress, escrow arrangements, SPA and expected completion information. Dubai’s Law No. 8 of 2007 provides for project escrow accounts that are protected from attachment by the developer’s creditors. This safeguard does not remove construction, delay, valuation or buyer-payment risks.
If a buyer stops paying, Dubai Law No. 19 of 2020 sets out circumstances in which a developer may retain up to 40% of the unit’s value when project completion is above 60%, or up to 25% when works have started but completion is below that level. The law also provides for refunds if works have not started for reasons beyond the developer’s control, or if RERA cancels the project. Read the relevant provisions in Dubai Law No. 8 of 2007 and Dubai Law No. 19 of 2020. These legal provisions are general information, not advice on an individual case.
How much leverage may be available?
For an expatriate buyer, the Central Bank of the UAE’s mortgage rules set a maximum loan-to-value (LTV) ratio of 60% for an investment property. The rules allow up to 80% for an expatriate’s first home valued below AED 5 million, and set a 50% maximum for an off-plan purchase. The first-home limit should not be assumed to apply to an investment property. See the CBUAE mortgage-loan regulations and ask a lender to assess your circumstances before committing.
For an off-plan buyer, the mortgage limit while the property remains under construction can mean a larger cash requirement than expected. At handover, financing may depend on the completed property’s valuation, the lender’s criteria and the buyer’s eligibility. Do not treat a possible loan as certain until the lender has assessed it.
What foreign buyers get wrong in Dubai off-plan, what each mistake costs, and exactly what to do instead.
Download free→One three-year cash-flow comparison
The following is one illustrative worked comparison for this 2026 guide. The ready-property rent assumptions are drawn from M&M’s rental and yield analysis, while the off-plan payment structure follows its Arancia case. It compares a cash purchase of a ready home with staged payments for an off-plan home; it is not a forecast or a like-for-like comparison of mortgage strategies.
- Ready JVC one-bedroom: The purchase price is AED 1,100,000, and the modelled all-in cash requirement on day one is AED 1,171,820. Modelled net rent is AED 53,750 a year. Over three years, AED 53,750 × 3 = AED 161,250 in net rent.
- Off-plan Arancia one-bedroom: The purchase price is AED 1,000,000 on a 40/60 plan. Staged payments of 40% equal AED 1,000,000 × 0.40 = AED 400,000. Oqood adds a 4% fee plus AED 20: AED 1,000,000 × 0.04 + AED 20 = AED 40,020. Before keys, the model therefore puts AED 400,000 + AED 40,020 = AED 440,020 into the purchase. The remaining 60% is AED 1,000,000 × 0.60 = AED 600,000, due at handover.
In this illustration, the ready buyer commits more cash upfront and receives rental income during the three-year period. The off-plan buyer has paid less before handover but earns no rent from the unit during that time, then faces the remaining payment. If the completed property is valued at AED 1,000,000 and the buyer qualifies for 60% investment-property finance, a AED 600,000 loan could cover that balance. This is conditional on lender approval and valuation; it is not a promise of finance.
The comparison shows the cash-flow trade-off, not which property will perform better overall. The ready buyer has income sooner, while the off-plan outcome depends in part on delivery timing, the valuation at handover and available finance.
A portfolio idea for international investors
Rather than treat the choice as all-or-nothing, consider how each property would serve a different role. A ready home may suit an investor who wants rental income sooner and can commit more capital upfront. An off-plan home may suit someone able to meet staged payments without relying on rent during construction, while accepting that the delivery date and future valuation are not certain.
Before buying, test each option against your available cash, income needs, borrowing plans and holding period. Avoid relying on an assumed resale uplift or rent figure to make the numbers work. M&M’s guide to common off-plan buying mistakes offers further checks for a project purchase.
The DLD property-investor route is a 10-year residence permit. DLD’s application information sets out a total purchase-value threshold of AED 2,000,000 or more, with the property or properties wholly owned in the applicant’s name. For a mortgaged property, the DLD page requests a bank letter showing AED 2,000,000 paid and a no-objection letter stating the paid amount and outstanding balance. Cabinet Resolution No. 65 of 2022 includes off-plan units from approved developers. Eligibility and documentation depend on the current rules, so check the DLD Golden Visa application requirements and the Cabinet Resolution before relying on a property purchase for residency. This is general information, not visa advice.
Should tax affect my choice?
Tax treatment depends on your circumstances and the rules in the countries relevant to you. An international buyer should obtain independent legal and tax advice before purchasing, renting or selling a Dubai property.
Make the decision around your cash flow
Ready and off-plan property serve different investment plans. Ready can put a home into use sooner and may bring rent earlier, while off-plan spreads payments but delays income and leaves delivery, valuation and financing questions to resolve. Compare the cash required at each stage, verify the project or property, and make sure the plan still works if handover or finance differs from your expectation.
For advice based on your investment goals and funding plan, speak with M&M Real Estate.
Is a ready or off-plan property better for rental income?
A ready property can usually be rented sooner, subject to its condition, tenancy status and preparation. An off-plan home generally produces no rent until it is completed and ready to let. Compare expected income after relevant costs rather than relying on a gross-yield benchmark.
Can an international buyer get a mortgage for an off-plan property?
CBUAE rules set a 50% maximum LTV for an off-plan purchase. The lender still assesses the applicant, property and transaction, and its approval should not be assumed. For a completed investment property, the stated expatriate maximum is 60%, subject to the applicable rules and lender assessment.
Do ready and off-plan purchases both have a DLD fee?
Yes. DLD’s published schedules set a 4% fee for both routes. An off-plan initial sale is registered through Oqood at 4% plus AED 20. Check the relevant DLD service for the transaction process and applicable charges.


