

Our guide to Dubai’s first-time home buyer programme in 2026 explains who qualifies and what benefits may apply, with practical steps for registration, financing and property due diligence. Eligibility is a useful starting point, not a substitute for checking the full cost of buying and owning a home.
Key Takeaways
| Question | What to know |
|---|---|
| Who may qualify? | UAE nationals and UAE residents can apply if they meet the programme’s age, property ownership and property-value criteria. |
| What benefits may be available? | Offers can include priority access, preferential pricing, payment support and mortgage options. Participating partners set their own terms. |
| Does eligibility guarantee a mortgage? | No. A participating bank assesses each borrower separately and decides whether to offer finance. |
| Can buyers compare developers? | Yes. Compare the written terms and property details from each participating developer, rather than choosing on a headline offer alone. |
| How should I choose an area? | Match the home to your budget, intended use and ownership costs. Our guide to Dubai property locations can help structure that comparison. |
| Where can I find more guidance? | Use our Dubai property resources to support your wider purchase planning. |
Who qualifies for Dubai’s first-time buyer programme?
The programme is aimed at UAE nationals and UAE residents buying a first home in Dubai. The Dubai Land Department’s programme overview says applicants must be 18 years or older and seek a property below AED 5 million in value. Read the Dubai Land Department’s eligibility overview.
The ownership test focuses on existing freehold residential property in Dubai. The programme’s ownership test concerns existing freehold residential property in Dubai, rather than home ownership anywhere in the world.
If your ownership history is complex, ask the programme administrator how the ownership test applies to your circumstances before relying on eligibility.
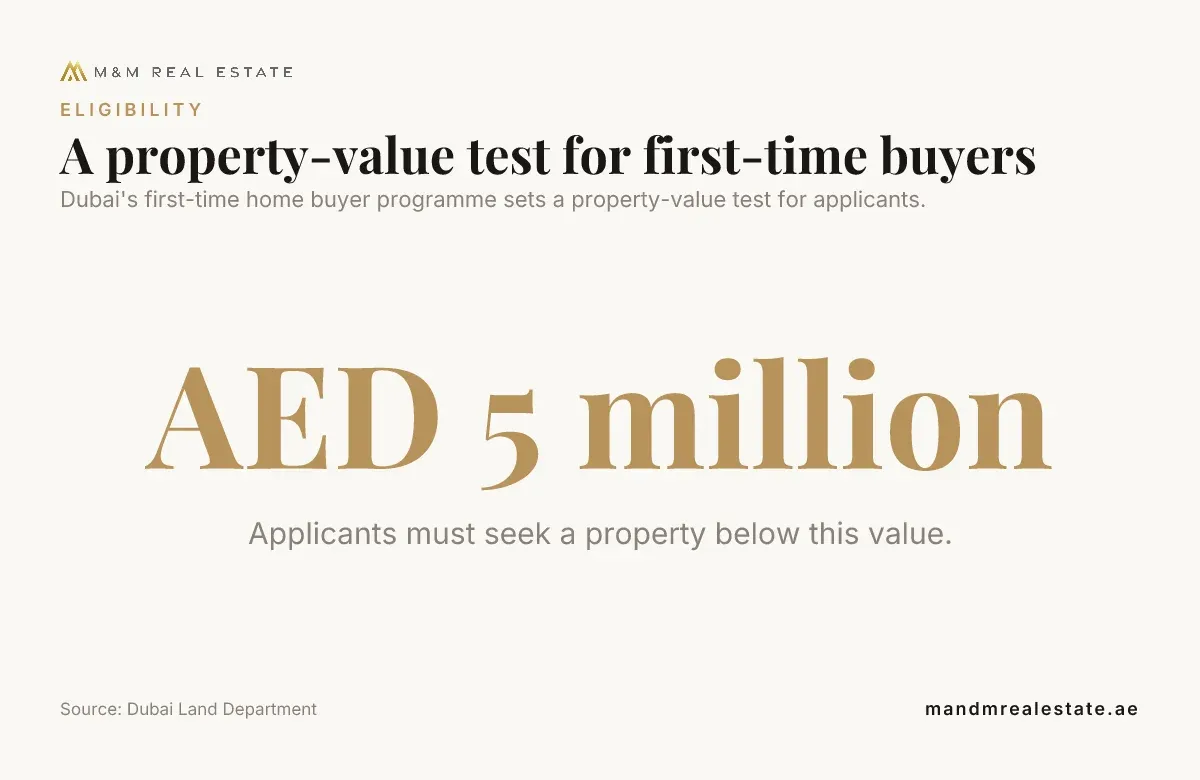
Dubai’s first-time home buyer programme sets a property-value test for applicants.
Source: Dubai Land Department
Before committing, review the unit terms and final purchase price.
What benefits may the programme offer?
Benefits may include access to selected homes, preferential pricing or discounts, payment options for the DLD registration fee, and mortgage offers from participating banks. Not every benefit applies to every buyer or property, so ask each partner for its written terms and compare the conditions attached to the offer.
Dubai Department of Economy and Tourism’s programme update reports that the programme has enabled more than 3,200 residents to own their first homes in the emirate since its launch in July 2025, generating residential property transactions exceeding AED 5 billion. See the Dubai Department of Economy and Tourism update.
A discount or payment plan can improve the timing of a purchase, but it does not automatically make the home affordable. Compare the offer with the full price, all transaction charges, ongoing ownership expenses and the timing of each payment.
How to register and use your eligibility confirmation
Start with the official programme registration process and provide accurate identity and ownership information.
- Register before committing. Understand the eligibility criteria before committing to a specific home.
- Compare partners. Ask developers to explain the unit, price, payment plan and conditions in writing. Ask banks to set out the financing structure and any fees.
- Keep eligibility in perspective. Compare any partner offer with your budget and the home’s terms.
- Separate programme charges from purchase charges. Ask for an itemised statement of property registration and other transaction expenses.
Registration does not require you to take a mortgage. Cash buyers can assess developer offers and any relevant access or pricing benefits, while bank-specific financing terms only apply if a buyer seeks and receives a loan.
Mortgage pre-approval is separate from programme eligibility
What are the requirements to qualify for a home loan in the UAE? Banks commonly assess income, employment or business records, existing debts, credit history, account statements and the property being purchased. Each lender applies its own underwriting criteria, so programme eligibility does not guarantee approval or a particular interest rate.
Is it difficult to get a mortgage in Dubai? The process is manageable when your documents and budget are ready, but approval depends on the lender’s assessment of your finances and the property. Request mortgage pre-approval early, then ask the bank to explain the expected instalments, fees, rate terms and conditions that could change before completion.
Use this sequence before paying a reservation amount:
- Set a monthly payment limit that leaves room for regular living costs and savings.
- Gather income, bank and debt documents, then request pre-approval from a participating bank.
- Ask how the lender will treat the chosen property and payment schedule.
- Rework the budget using the bank’s actual terms, then review the reservation and refund conditions.
Build resilience into the decision. Consider whether the home would remain affordable if your income fell, financing costs changed or ownership expenses rose; do not base the purchase on the most favourable scenario alone.
Twelve chapters on what the regional war tested, the balance sheet and dollar peg behind the market, and how to pick the right side of this cycle.
Download free→Budget for the full cost, not just the home price
Beyond the property price and DLD registration fee, buyers may need to budget for a trustee or conveyancing service, an agency fee, mortgage registration and valuation costs, bank charges, insurance, service charges, utilities and maintenance. Which costs apply depends on the property and transaction, so request a full cost schedule before signing.
Separate one-off purchase expenses from recurring ownership costs. If you plan to rent the home, assess likely vacancy periods and operating costs as well as rent; our guide to Dubai rental yields and costs offers a framework for that assessment.
Worked property-value check: Start with the programme limit of AED 5 million, then subtract the property price; the result is the amount below the limit. The property must be below AED 5 million, as stated in the Dubai Land Department eligibility overview.
Dubai property ownership does not mean ignoring tax and recurring charges. Review the rules that apply to your own situation using our guide to tax on Dubai property.
Choose a location that fits your plans
Start with how you will use the home. A property for your own household calls for a different comparison from a purchase you expect to rent out or hold as a longer-term investment.
Compare commute, services, building condition, service charges and resale or rental demand in the areas you are considering. Our guides to Dubai areas and investment goals and Dubai property investment can support that assessment.
A programme incentive should support your choice, not determine it. Compare the property’s location, layout, condition and total cost with your real needs before weighing any priority access or preferential pricing.
Off-plan or ready property: carry out due diligence
The programme may offer access to off-plan and existing homes, but the checks differ. An off-plan property asks you to assess a project and future delivery, while a ready property lets you inspect the home and building before completion.
For an off-plan purchase, review the developer’s record, project documentation, payment milestones, escrow arrangements, sale agreement and handover terms. Make sure the schedule works with your cash flow and that you understand what happens if construction or handover timing changes.
Our Dubai off-plan property listings and off-plan buying guide can help you organise the comparison.
For a ready home, inspect the property and shared areas, review the title and service-charge position, and understand the seller’s completion requirements. In either case, do not treat a programme registration or early-access invitation as a guarantee of a particular unit, price or allocation.
No, programme eligibility and property-based residence eligibility are separate matters. If a Golden Visa is also part of your plan, review the distinct requirements in our Dubai Golden Visa property guide.
The Dubai first-time home buyer programme can give eligible residents access to partner offers, but the value depends on the property, the written terms and your financing position. Check the Dubai freehold ownership test, secure mortgage pre-approval if you need a loan, and compare the full purchase and ownership costs before committing.
That is how we approach a first purchase: real affordability, clear due diligence and advice without noise. For anyone asking who qualifies for Dubai’s 2026 first-time buyer programme and what benefits may apply, the answer starts with your eligibility and ends with whether the home fits your plans.
Can a buyer who lives outside the UAE apply?
Applicants are UAE nationals or UAE residents. Property ownership rights and programme eligibility are separate questions.
Can two people buy together if only one meets the criteria?
For a joint purchase, ask the programme administrator how it assesses each person on the title, and have the lender assess every proposed borrower.
Can I use programme eligibility for a second purchase?
Ask the programme administrator how a later purchase is treated before making a new commitment.
How long does eligibility confirmation take, and what should I do if the application is declined?
Allow time for the application review and avoid making an irreversible payment based on an assumed approval date. If the application is declined, request the reason, correct any identity or ownership details that need updating, and ask the administrator about the review process.
Can a family member use my eligibility confirmation?
A family member should confirm their own eligibility with the programme administrator before relying on yours for a purchase.


