Many buyers make Dubai property investment mistakes when they choose a unit before deciding what they want the investment to achieve. A clear plan helps you compare opportunities on their merits, understand the risks and choose an asset that fits your finances and time horizon.
At M&M Real Estate, we believe an investment decision should rest on more than a compelling brochure or payment offer. Start with the purpose of the purchase, then test the property, location, developer and costs against that goal.
Buying before defining your investment strategy
A property can be attractive and still be wrong for your portfolio. Before viewing options, decide whether your priority is rental income, long-term value growth, a future home, or a combination of these. Each goal calls for a different assessment of location, property type, tenant profile and holding period.
Be specific about the return you need and the amount of capital you can commit. Consider how quickly you might need access to those funds, whether you can manage a property from abroad and how much uncertainty you are comfortable carrying. These questions help distinguish a suitable investment from an appealing but poorly matched purchase.
Write down your assumptions before comparing properties. If your decision depends on a particular rent, resale price or handover date, record where that expectation comes from and what could cause it to change. Treat projections as estimates to test, not outcomes to rely on.
Choosing an area without checking the local market
A district’s reputation does not tell you whether a particular property will suit your strategy. Look closely at the immediate surroundings, access to transport and everyday services, the types of homes nearby and the properties that may compete for the same tenants or buyers.
Compare like with like. A waterfront apartment, a family home and a compact unit designed for tenants serve different markets, even if they sit within the same broad area. Review relevant recent transactions and rental evidence, and make sure the properties you compare share similar features, condition and location.
Visit the area if possible. If you cannot, ask for clear information about the building, access, nearby development and the outlook from the unit. A location can look persuasive in a presentation while raising practical questions that affect tenant demand or future resale.
Confusing the advertised price with the full cost
The purchase price is only one part of an investment decision. Allow for ownership and operating costs such as service charges, maintenance, property management, financing and any applicable transaction costs. If you plan to rent the unit, account for periods without a tenant and the work needed to prepare or maintain it.
Ask for a complete cost schedule and check which items are confirmed, estimated or excluded. If you are buying from overseas, consider how currency movements and tax obligations in your country of residence could affect your overall position. Get specialist advice where needed rather than assuming the Dubai purchase is your only financial or tax consideration.
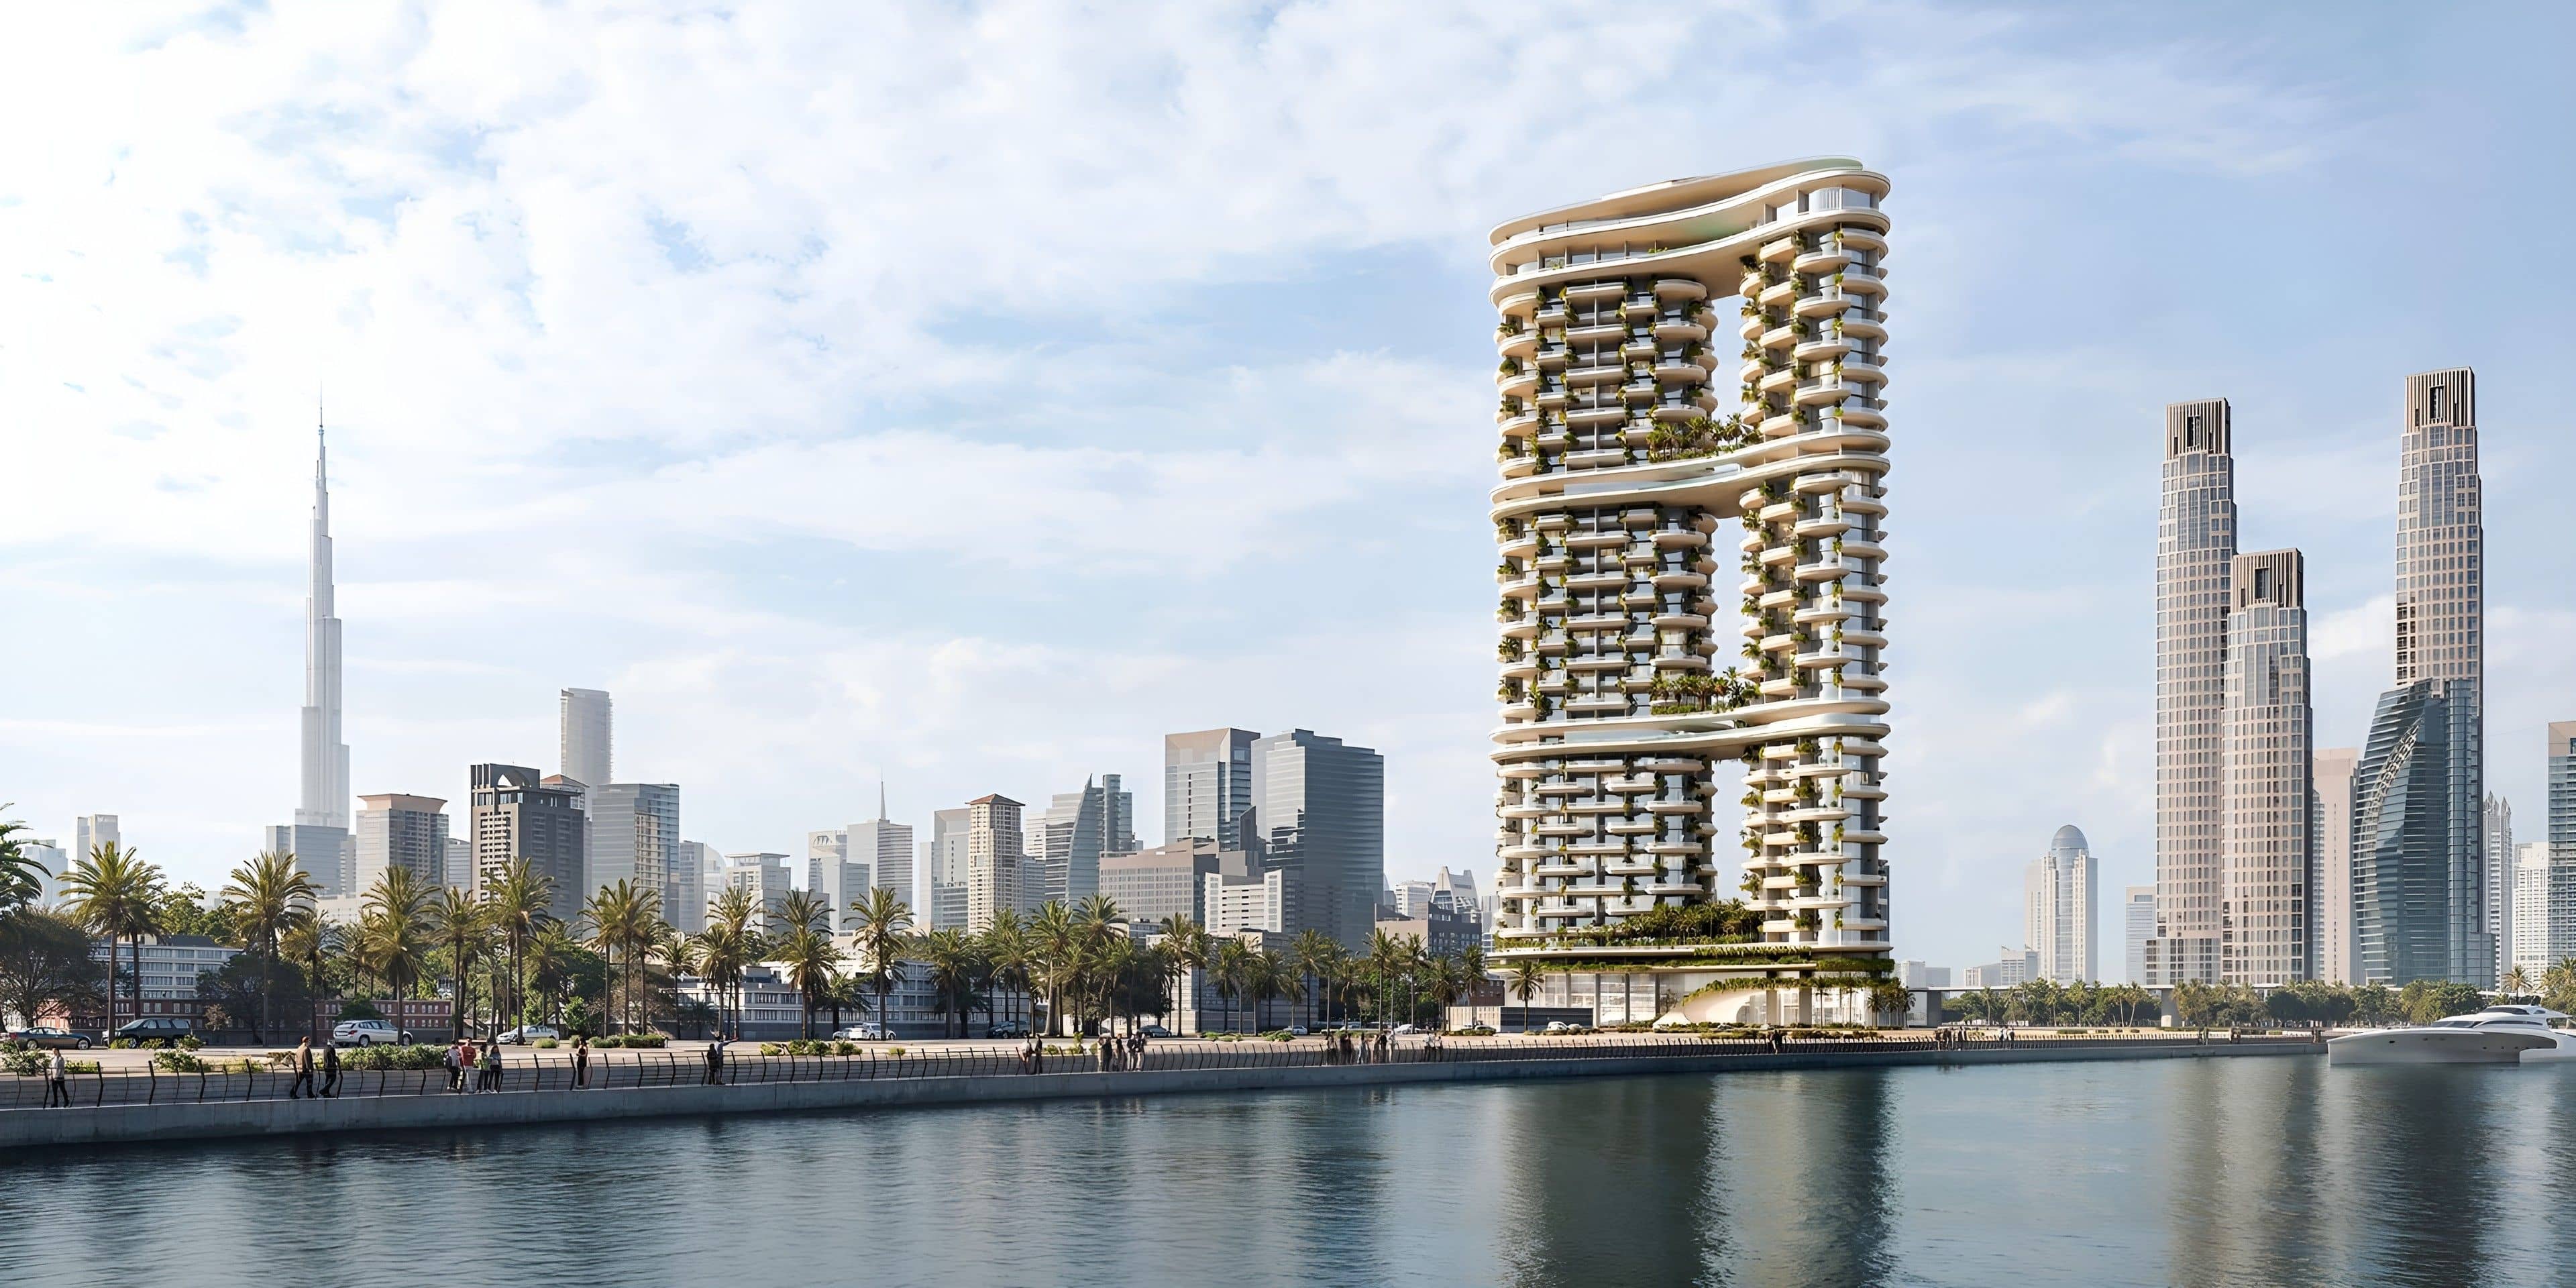
For a simple illustration, M&M Real Estate lists a two-bedroom entry price of AED 15.3 million and a 60/40 payment plan for Amali Residences. Worked example, using the terms on the Amali Residences investment case, accessed in 2026: AED 15,300,000 × 60% = AED 9,180,000; AED 15,300,000 × 40% = AED 6,120,000; AED 9,180,000 + AED 6,120,000 = AED 15,300,000 in total. The case states that the remaining 40% is due on completion, so an investor should consider how that future payment fits their own funding plan.
This calculation covers the listed purchase price and payment split only. It does not include other ownership or transaction costs, which should be checked separately before committing.
What foreign buyers get wrong in Dubai off-plan, what each mistake costs, and exactly what to do instead.
Download free→Relying on marketing material instead of due diligence
Project visuals can help you understand a proposal, but they are not a substitute for checking the details behind it. Review the floor plan, specifications, included fittings, payment terms and contractual documents. Confirm what the developer has committed to deliver and what remains subject to change.
Research the developer’s delivery record and be candid about any gaps. M&M’s Amali case, for example, notes that the developer had not yet handed over a project at the time of assessment. That does not determine the outcome of a new development, but it is a relevant consideration when weighing execution risk against the project’s appeal.
Look beyond headline amenities, too. Ask whether the facilities suit the likely resident or tenant, how they will be maintained and whether the expected service costs fit your rental assumptions. An extensive amenity list may support a project’s positioning, but it does not by itself prove future demand or income.
Misreading an off-plan payment plan or handover date
A payment plan changes when capital is due; it does not remove the need to assess the total commitment. Check the instalment triggers, the amount due at completion and the funds you will need if construction or your own circumstances do not follow your preferred schedule.
Pay close attention to the handover estimate. Read the contract, understand the stated terms and consider how a delay could affect your financing, rental plans or intended resale.
Do not assume you can sell an off-plan property whenever you choose or on terms that suit you. Check the contractual and practical conditions that apply to resale, and avoid building your strategy around an exit that you have not verified.
Assuming a payment schedule proves the investment works
Manageable instalments can make a purchase seem easier to afford, but the schedule says little about the property’s value as an investment. Assess the full amount committed, the timing of payments and the evidence for expected rent or resale demand. A long payment period can also leave you exposed to changes in your plans or the market before the property is complete.
Empire Estates in Arjan illustrates why buyers should check the terms carefully. The project page describes apartments and duplexes, including studio, one-bedroom and two-bedroom layouts, and lists a plan with a 20% down payment followed by 1% monthly for 80 months. The page does not state a purchase price and invites buyers to ask about current availability and pricing. See the Empire Estates project page, accessed in 2026 for the project information.
Before comparing a plan with other opportunities, request current prices and confirm the complete payment schedule in writing. Then test whether the property still suits your strategy when you account for ongoing costs, expected demand and the possibility that your preferred exit takes longer than planned.
Ignoring the exit before you buy
Every investment plan should include a view of how you might eventually sell, refinance or retain the property. Consider who the next buyer or tenant could be, what features they may value and whether similar homes compete for their attention. A property that works for your own preferences may not appeal to the market you need.
Think through more than one outcome. If rent falls short of your estimate, the handover takes longer than expected or you need to sell earlier than planned, would the investment remain manageable? A plan that depends on a single favourable outcome leaves little room to respond when circumstances change.
Putting too much capital into one type of property
Concentration can arise when several purchases depend on the same area, tenant group, property type or completion timeline. Before adding another asset, assess how it changes your overall exposure. A new purchase should improve the fit of your portfolio, not simply increase its size.
Review your existing commitments alongside the proposed purchase. Consider how much capital remains available for other needs and whether your holdings rely on similar assumptions about rental demand, resale or project delivery. If you are building a portfolio, an independent review can help reveal where your investments overlap.
Making a stronger investment decision
Good property decisions come from asking disciplined questions before committing. Define the purpose of the purchase, verify the local market evidence, account for ownership costs and assess the developer, contract, payment terms and exit options. Keep a written record of assumptions and revisit them when new information emerges.
At M&M Real Estate, our investment cases and portfolio reviews are designed to help buyers examine both the appeal and the drawbacks of an opportunity. The aim is not to remove uncertainty, but to make the decision with a clear view of what you are buying, what could change and how the property fits your wider plans.
A property’s presentation and payment schedule can draw attention, but neither tells the whole investment story. Take time to test the evidence, assess the costs and understand the commitments before you proceed. A strategy-led approach helps you compare opportunities with care and avoid decisions that do not support your financial goals.