A UK resident can owe UK Capital Gains Tax when selling Dubai property because UK tax may apply to gains on overseas property.
How UK tax residence affects a Dubai property sale
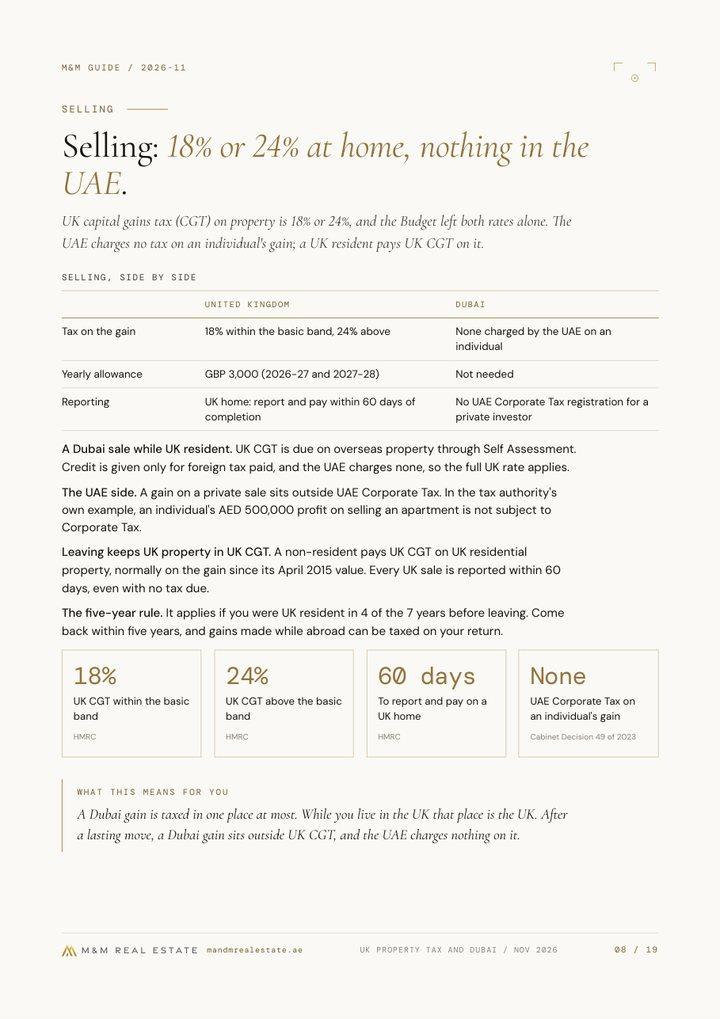
If you are UK tax resident when you dispose of overseas property, you generally need to consider UK Capital Gains Tax on the gain. GOV.UK’s guidance on selling overseas property sets out this rule.
The Statutory Residence Test determines UK tax residence using factors such as days spent in the UK and your ties to the country. Your citizenship or a UK address alone does not decide the test. The relevant question is your residence status for the tax year of the disposal.
Some people may qualify for a regime covering overseas gains, subject to eligibility conditions. See GOV.UK’s guidance on the foreign income and gains regime for its eligibility conditions.
A move to or from the UK around the sale date can change which rules apply. We advise investors to establish their tax residence for the relevant year before they plan the disposal.
The UAE tax position and the UK and UAE treaty
The UAE tax treatment of property gains depends on the circumstances; UAE Cabinet Decision No. 49 of 2023 sets out relevant rules.
That UAE treatment does not remove a UK resident’s possible UK tax bill. The UK and UAE have a double taxation treaty.
Any foreign tax paid may be relevant when considering UK relief; see GOV.UK’s foreign tax credit relief guidance.
This is general information, not tax or legal advice.
Calculate the gain in sterling
For UK Capital Gains Tax, calculate the gain in sterling, considering disposal proceeds, acquisition cost and any allowable costs. Consider reliefs separately.
This means exchange-rate movements can change the UK taxable gain even when the AED difference between purchase and sale stays the same. For an off-plan purchase paid in stages, record every payment and its sterling value on its transaction date.
Keep the sale and purchase contracts, payment confirmations and exchange-rate workings together. Each amount should be traceable to its date and supporting record.
For investors considering staged off-plan payments, Property for Sale in Dubai is relevant because M&M Real Estate guides investors with a focus on off-plan apartments and waterfront projects for high-end investors. Separate payment dates can create separate sterling acquisition entries.
Use transaction-date exchange rates when converting amounts to sterling.
Allowable costs can reduce the taxable gain, so keep each receipt and sterling calculation with the sale records.
For more on payment schedules and the purchase process, see our Dubai off-plan guide.
Allowable costs and ownership structure
Costs directly linked to buying or selling the property may be relevant to the gain if they meet UK rules. Capital improvements that add to or alter the property can be different from routine repairs, maintenance and service charges, which are not automatically allowable costs.
For jointly owned property, calculate each owner’s share using the beneficial ownership and keep records of how the owners divided the purchase cost, sale proceeds and expenses. The ownership documents should support each person’s calculation.
Company ownership can raise separate tax questions.
If the sale produces a loss, calculate it in sterling using the transaction-date rates and keep the evidence. Report the loss under the applicable rules; a properly claimed loss may be available to offset eligible gains.
What thousands of high-net-worth British residents are doing right now, the forces pushing them, and what Dubai offers in 2026.
Download free→Reliefs and a return to the UK
Private Residence Relief may apply if the Dubai property qualified as your only or main residence and the statutory conditions are met. A holiday home or investment property does not qualify solely because you stayed there.
Selling while non-resident can leave a UK tax question if you later return. HMRC’s temporary non-residence rules can bring certain gains realised while abroad into charge when you return, depending on your residence history.
If you had sole UK residence in four or more of the seven tax years before leaving, and were away for five years or less, certain gains realised during the absence can be taxed on your return. This rule comes from HMRC’s Statutory Residence Test guidance, updated on 11 Jun 2026.
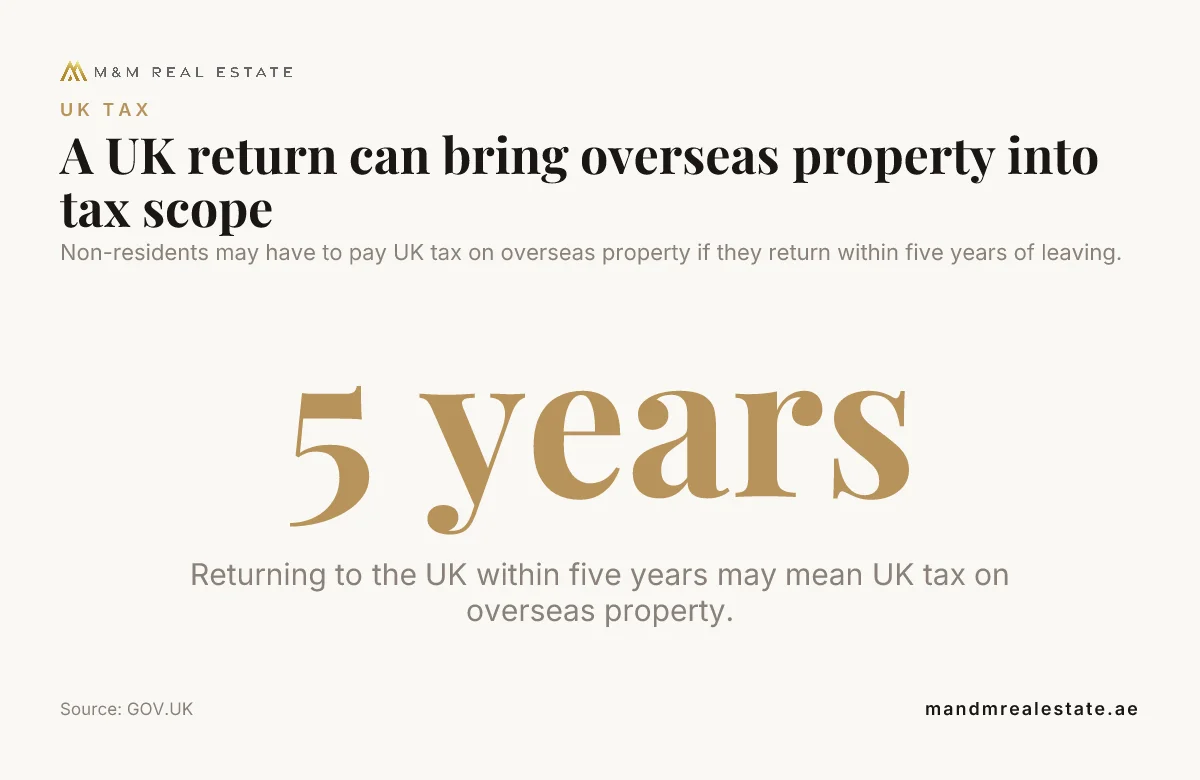
Non-residents may have to pay UK tax on overseas property if they return within five years of leaving.
Source: GOV.UK
The five-year period is a prompt to review the sale date alongside your residence history. It does not make every gain during an absence taxable. Confirm with a UK tax adviser whether your costs qualify and whether Private Residence Relief applies.
Rates, income and the annual exempt amount
The bill depends on the taxable gain after allowable costs, reliefs and the annual exempt amount. The rate also depends on your taxable income and the tax year of disposal.
For 2026-27, GOV.UK’s Capital Gains Tax rates state that higher and additional rate taxpayers pay 24%. Basic rate taxpayers pay 18% on gains within the unused part of their basic rate band, then 24% on gains above it. The annual exempt amount is GBP 3,000 for that tax year.
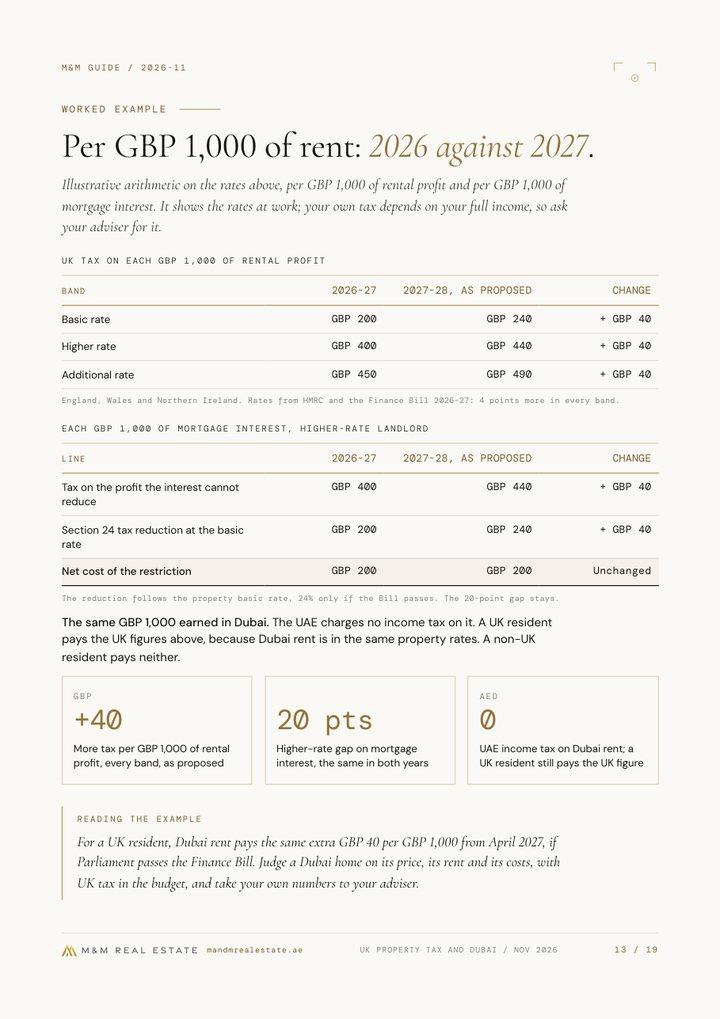
GOV.UK’s income tax rates for 2026-27 set the basic rate band at taxable income from GBP 12,571 to GBP 50,270. Salary and other taxable income use part of that band, so the amount left for a gain can affect the rate applied.
Use the rates and thresholds for the tax year of the disposal. If you claim the four-year foreign income and gains regime, remember that the claim removes the Capital Gains Tax annual exempt amount for that year.
Report the sale and keep a usable audit trail
A UK tax resident will generally report a taxable Dubai property disposal through Self Assessment, following the filing and payment deadlines for the relevant tax year. For disposals in 2025-26 and 2026-27, UK residents can also use HMRC’s real-time Capital Gains Tax service. GOV.UK’s reporting guidance says to report through that service by 31 December after the tax year and pay by 31 January.
The 60-day UK residential property return applies to UK residential property. A Dubai sale follows the reporting route for other gains, so keep the foreign property calculation and supporting records ready for the relevant return.
- Keep the purchase and sale contracts, including the dates and agreed amounts.
- Save staged-payment records and the sterling conversion for each payment and receipt.
- Retain invoices for improvements, selling costs and any claimed acquisition costs.
- Keep ownership documents, foreign tax records and evidence supporting a claimed loss.
For wider context on tax comparisons, capital transfers, investment structures, the Golden Visa and the buying process, the British investor guide covers Dubai investment from a UK perspective. Use that broader context alongside advice based on your own disposal, residence history and costs.
See also: Dubai Golden Visa through Property: 2026 Guide, Which Dubai Property Area Fits Your Investment Goal in 2026?, Property Developers in Dubai: Profiles and Track Records, Dubai Rental Yields in 2026: Gross Returns, Costs and Tax, What Investors Need to Know About Tax on Dubai Property, Dubai Property Investment in 2026, Off Plan Properties in Dubai, Best Areas to Invest in Dubai and Abu Dhabi, Dubai Investment Guides & Resources, Bay Estate by Nakheel, Dubai Islands: Investment Case, The Yards Plaza by BEYOND, City of Arabia Offices, Emaar and DAMAC: How to Compare Two Projects on the Public Record, Al Jaddaf Waterfront Guide 2026: Prices and Metro, 30/70 Payment Plan: What Beyond’s Offer Changes, JVC (Jumeirah Village Circle) Investment Guide 2026, Dubai Hills Estate Guide 2026: Prices and Yields, Dubai population growth is reshaping how the city plans for residents, How Dubai Property Crowdfunding Works: Shares, Returns and Risks, The Yards Plaza by BEYOND, City of Arabia Offices, M&M.
What to do now
Before agreeing a sale, establish your UK tax residence for the relevant year and assemble the sterling value of each purchase payment, improvement and sale receipt. Separate potential capital costs from routine upkeep, then list the reliefs, ownership shares and reporting route that may apply.
An M&M advisor will go through your Dubai purchase records, ownership route and sale timeline with you. Contact M&M.
this article is general information and not tax, legal or financial advice, and returns are not guaranteed.
Does paying off the mortgage reduce the capital gain on a Dubai property?
No. Mortgage repayments do not change the property’s acquisition cost or its disposal proceeds, although settling the loan reduces the cash left after the sale completes. Keep the lender’s redemption statement with your sale records.
Is rental income from a Dubai property taxed separately from the gain when it is sold?
Yes. UK tax on rental income and Capital Gains Tax on a later sale are separate calculations. Keep rental receipts and expenses apart from the purchase, improvement and sale records used for the gain.
Can I defer UK Capital Gains Tax by reinvesting the sale proceeds in another property?
Reinvesting the proceeds in another Dubai property does not by itself defer UK Capital Gains Tax. Ask a UK tax adviser to assess whether a specific statutory relief applies to your circumstances before committing to another purchase.
How is the acquisition value worked out if I inherited or was gifted the Dubai property?
For an inherited property, the UK CGT acquisition value is generally its market value at the date of death. A gift can be treated using market value under connected-person rules, with exceptions for some transfers, so retain the estate or gift valuation and have the transfer history reviewed by a UK tax adviser.
UK property tax changes and Dubai
What the 28 October Budget changes for UK landlords, set beside what Dubai charges to buy, own, let and sell. 19 pages. Free by email.