


How do Dutch investors buy off-plan property in Dubai with a payment plan? Start by matching every instalment in the sale and purchase agreement (SPA) to money you can access on its due date, then assess the project, contract, currency exposure and Dutch tax position.
- Compare the full payment schedule, including the handover balance and any post-handover instalments.
- Check whether payments follow construction milestones or fixed dates, and test how each schedule fits your expected holding period.
- Verify project registration and escrow details through Dubai Land Department channels. Escrow safeguards project funds, while delivery and market risks still need separate assessment.
- Build a cash plan in euros for each AED payment, with room for exchange-rate changes and costs outside the developer’s instalments.
- Ask a qualified Dutch tax adviser how foreign property and financing may be treated under Box 3 and any relevant treaty relief.
- Keep the SPA, registration records and payment confirmations together, whether you sign in Dubai or from the Netherlands.
How Dubai off-plan payment plans are structured
A developer payment plan sets out when the buyer pays the reservation amount, down payment, construction instalments and handover balance. The SPA records the unit, payment triggers and due dates, so the full schedule determines the cash commitment, not the booking amount alone.
Construction-linked instalments fall due when the developer reaches stated building milestones. Fixed-date instalments fall due on set dates, which can mean a payment is due even when visible construction progress is limited.
| Plan structure | What triggers payment | What to assess |
|---|---|---|
| Construction-linked | A stated construction milestone | How the milestone is defined and confirmed in the SPA |
| Fixed-date | A date in the payment schedule | Whether funds will be available on each date |
| Handover-heavy | A larger balance when the unit is completed | How that balance will be funded if lending terms change |
| Post-handover | Instalments after completion | How long payments continue and whether they fit the exit plan |
When reviewing a Mudon community payment plan, compare its handover balance with the cash you expect to have available.
Compare the amount due at handover with any later instalments. A small initial payment can leave a large future funding need, while a post-handover payment plan extends the commitment after the unit is ready.
The Dubai Off-Plan Guide explains payment mechanics, escrow protections, legal protections and transaction costs. Use the SPA for the terms of the particular unit, then compare those terms with the schedule before paying a reservation amount.
Match the schedule to your investment horizon and funding
Set your intended holding period and likely exit point against every instalment date. A plan that runs beyond handover may not suit an investor who expects to sell or refinance earlier, because the contract can leave payments due after the expected exit.
Rent starts only when a property is ready to let. For that reason, rental income cannot fund construction instalments, and projected rent after handover may not cover later payments once vacancy and running costs are included.
For market context, see our Dubai property investment guide and guide to Dubai rental yields, costs and tax. They help frame the investment case; each unit still needs its own cost and income assessment.
Plan the handover payment using funds you can access, rather than relying on future mortgage approval. Plan how to fund the handover balance and any costs outside the loan.
Stress-test the schedule against a delayed completion, a period without rent and a change in investment plans. The discussion of Dubai’s population growth can inform a demand case, while our area investment guide helps compare location factors; neither replaces a cash-flow test for the unit.
Assess the project, escrow arrangements and contract terms
Before paying, check the project’s registration and designated escrow details through Dubai Land Department channels. Match the project and account details to the property in the reservation documents, then keep a record of the information you verified.
Escrow governs how project funds are handled. Escrow governs how project funds are handled, but it does not remove construction, delivery or market risk.
Read the SPA for the unit description, payment triggers, completion provisions, late-payment consequences, cancellation rights, assignment conditions and resale restrictions. These clauses define how a buyer can respond if plans change or an instalment becomes difficult to meet.
Assess the developer’s delivery record, the project’s construction status and the location alongside any projected appreciation. M&M’s profiles of Dubai property developers set out factors to consider, including delivery history and fit with an investor’s needs.
Location assessment should include access, nearby amenities and the kind of tenant or buyer the property may attract. Compare Dubai location guides, including Al Jaddaf Waterfront, JVC and Dubai Hills Estate.
For examples of project-level review, read the The Yards Plaza Investment Case and its project analysis. A separate review of The Yards Plaza by BEYOND discusses the project in its City of Arabia context.
This is general information, not tax or legal advice.
What foreign buyers get wrong in Dubai off-plan, what each mistake costs, and exactly what to do instead.
Download free→Complete the purchase remotely from the Netherlands
A Dutch buyer can shortlist a unit, review its payment schedule and draft reservation terms, then proceed through reservation, SPA signing and the required Dubai Land Department registration. Oqood is the DLD’s off-plan registration, and the registration record belongs with the signed contract and payment confirmations.
Ask how the developer will complete identity checks and signing from abroad. If an authorised representative is needed, establish the power-of-attorney process and any notarisation or attestation requirements for the intended use with a Dubai lawyer.
M&M Real Estate curates off-plan property investment opportunities in Dubai, with developer access, ROI analysis and assistance from initial consultation through handover and beyond. Our property-buying guidance also covers investors considering off-plan apartments and waterfront projects.
Keep the signed SPA, registration records, project documents and proof of every transfer in one file. Plan euro-to-AED transfers ahead of each due date, allowing time for bank processing and currency conversion.
Our Dubai investment resources include material for international buyers. The purchase can be handled from abroad, while the buyer remains responsible for the payment dates and the documents supporting each transfer.
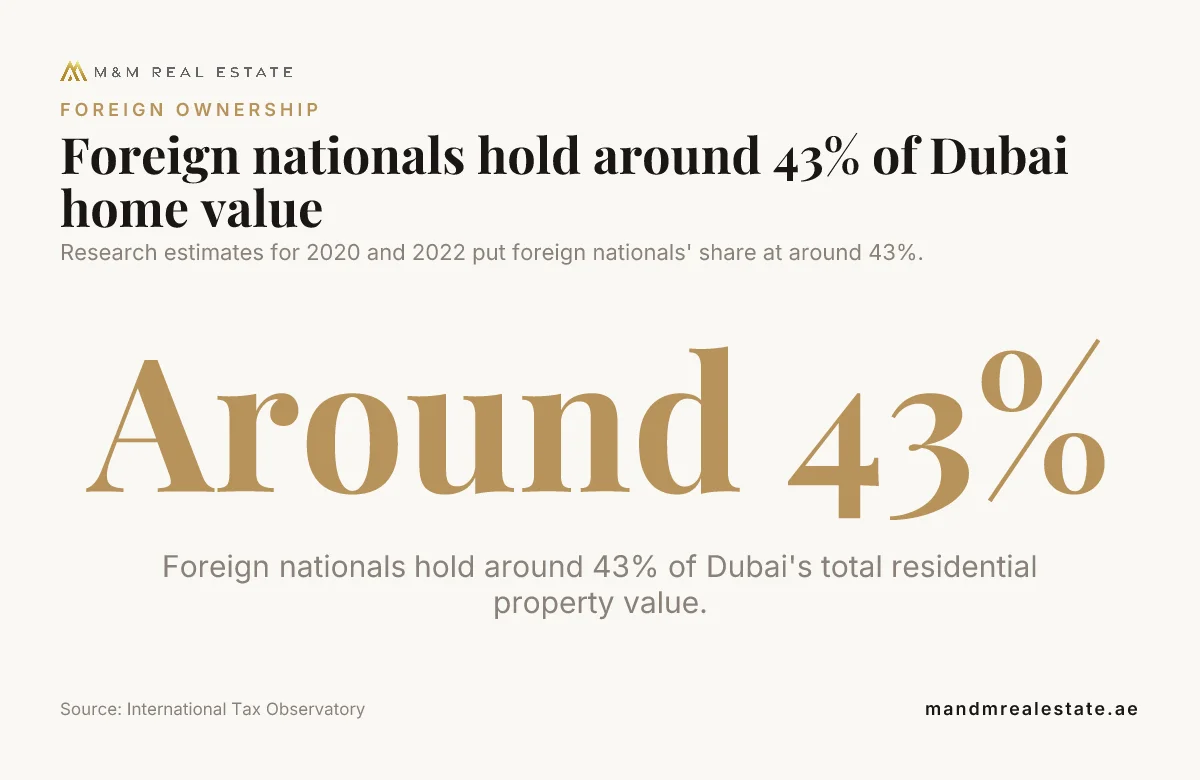
Research estimates for 2020 and 2022 put foreign nationals’ share at around 43%.
Source: International Tax Observatory
Budget for the full cost and test currency exposure
Developer instalments are only part of the purchase budget. Set aside separate amounts for registration and administration charges, financing costs, service charges and the cost of preparing or operating the property, because these bills can fall due on different dates.
Budget for the DLD transfer fee from the start.
Calculate each AED instalment in euros using more than one exchange-rate scenario. A change in the euro-to-AED rate can raise the euro amount needed for a scheduled payment even when the AED amount stays the same.
Keep a reserve for a payment during a delay, a period without rent or an unexpected property cost. Comparing direct ownership with pooled property exposure can also help clarify the commitment involved; our guide to Dubai real estate crowdfunding explains that separate approach.
Compare the contracted price and every scheduled payment with funds available on each due date. A low booking amount or projected rent alone does not show whether the full purchase is affordable.
Include Dutch tax residency in the investment decision
Ask a qualified Dutch tax adviser how foreign property may be reported and treated under Box 3, including how the property’s value and related financing enter the calculation. Ask how any Netherlands-UAE treaty provisions or relief mechanism apply to your own residency and ownership structure.
Discuss whether individual ownership or another structure fits the intended financing, reporting and eventual sale. Keep records of the purchase price, instalments, financing and transaction costs so your adviser can assess the actual structure.
The UAE levies no personal income tax on rent or capital gains, so a Dutch resident still needs to assess the Netherlands tax position. Read our guide to tax on Dubai property alongside advice for your own circumstances.
The Netherlands-focused guide Investing in Dubai from the Netherlands covers tax implications, capital transfer, investment structures, the Golden Visa and risks. M&M’s off-plan advisory supports global investors assessing Dubai projects and cross-border purchase decisions.
If residence is part of the decision, check eligibility requirements with the Dubai Land Department; our Dubai Golden Visa property guide explains the route.
This is general information, not tax or legal advice.
What to do before reserving
Put the SPA schedule into a dated cash plan, convert each AED instalment into euros under different exchange-rate scenarios, and identify the source of the handover balance. Then check project registration, escrow details, developer history, assignment terms and the Dutch tax questions with the relevant professionals.
M&M Real Estate is a Dubai property advisory firm with wealth advisors in Dubai, London and Breda. An M&M advisor will go through your budget, timeline and shortlist with you. Speak with an M&M advisor.
this article is general information and not tax, legal or financial advice, and returns are not guaranteed.

Can I get a home loan for an off-plan property in Dubai?
Possibly; ask the lender to assess the specific project and confirm when funds would be released.
How does a 1% payment plan in Dubai work?
The label usually describes instalments calculated as 1% of the property price at each scheduled payment. The developer’s SPA sets the dates and any separate reservation, registration or handover amounts, so compare the total schedule before reserving.
What happens if I cannot pay an instalment on time?
The SPA sets the applicable notice process, late-payment consequences and the developer’s contractual remedies. Contact the developer in writing as soon as a payment problem appears, and keep any agreed change in writing as part of the transaction record.
Can I sell or transfer an off-plan unit before handover?
The SPA and the project’s transfer requirements determine whether an assignment can proceed and what approvals or payments apply. Ask a Dubai property lawyer to review the transfer clause before buying if an early sale is part of the investment plan.
Is a reservation payment refundable if I change my mind?
Refund treatment depends on the signed reservation terms and the circumstances of cancellation. Read the clause that explains deductions, deadlines and the process for requesting repayment before sending the reservation amount.
Is it worth buying off-plan in Dubai?
It can be worthwhile if the project, location and payment schedule fit your investment goals and you can fund every instalment, including the handover balance. Consider the risks of delays, market changes and uncertain rental income, and assess the specific project and contract before committing.


