For Dubai apartment launches, a payment plan changes when cash is due, while the sale and purchase agreement (SPA) sets the purchase price and contractual obligations. M&M Real Estate’s SHIONE by BEYOND Investment Case is one example of a Dubai apartment launch.
Read the schedule from booking to handover
An off-plan property is bought before it is complete, with payments due at agreed stages. Start by mapping the booking payment, any further down payment, construction instalments and handover balance against their actual due dates. The off-plan guide explains the purchase process, and the off-plan properties in Dubai page provides context on current launch opportunities.
- Booking and down payment: Record how much is due at reservation and when any remaining initial payment must be paid.
- Construction instalments: Note the amount and due date of each instalment, including the milestone that triggers payment.
- Handover balance: Set aside the amount due when the developer completes and hands over the apartment.
- Post-handover instalments: Add any payments that continue after completion to the same timeline.
Construction-linked instalments fall due when the contract’s stated progress milestone is reached. Fixed-date instalments follow calendar dates, so read the contract’s definition of each milestone and what evidence certifies it.
A handover-heavy plan reduces earlier cash calls by postponing a larger share of the price, while leaving a substantial final amount to fund. A one-percent monthly plan describes recurring instalments of 1% of the stated price; the agreed schedule must set the price base, first due date, duration and treatment of the balance.
Put every due date in a calendar, then compare the full timeline with the funds you can access on each date. For background on planning a Dubai purchase, see M&M’s investor resources.
Compare construction-linked, fixed-date and post-handover plans
Each payment plan changes the timing and length of your commitment. Compare the contract terms, not just the name used to market the schedule.
| Plan structure | What it changes | What to examine |
|---|---|---|
| Construction-linked | Payments follow specified build milestones. | How the contract defines progress and certifies each milestone. |
| Fixed-date | Payments fall due on calendar dates. | Whether dates remain fixed regardless of visible construction progress. |
| Handover-heavy | A larger part of the price is due at completion. | How you will fund the final balance if borrowing or income changes. |
| Post-handover | Payments continue after the apartment is complete. | The length of the commitment and whether expected rent can cover costs. |
For a construction-linked plan, follow the contract’s milestone wording; a site visit alone does not set the payment date. A fixed-date schedule can make cash planning clearer, while still requiring payment on its stated dates.
M&M Real Estate’s SHIONE case page provides an example of an apartment launch.
A payment plan can spread part of the price across construction and leave a balance for completion. For comparison, review the terms in M&M’s analysis of a 30/70 payment plan, then check the schedule for the specific apartment you are considering.
Compare the full cash requirement, not the booking amount
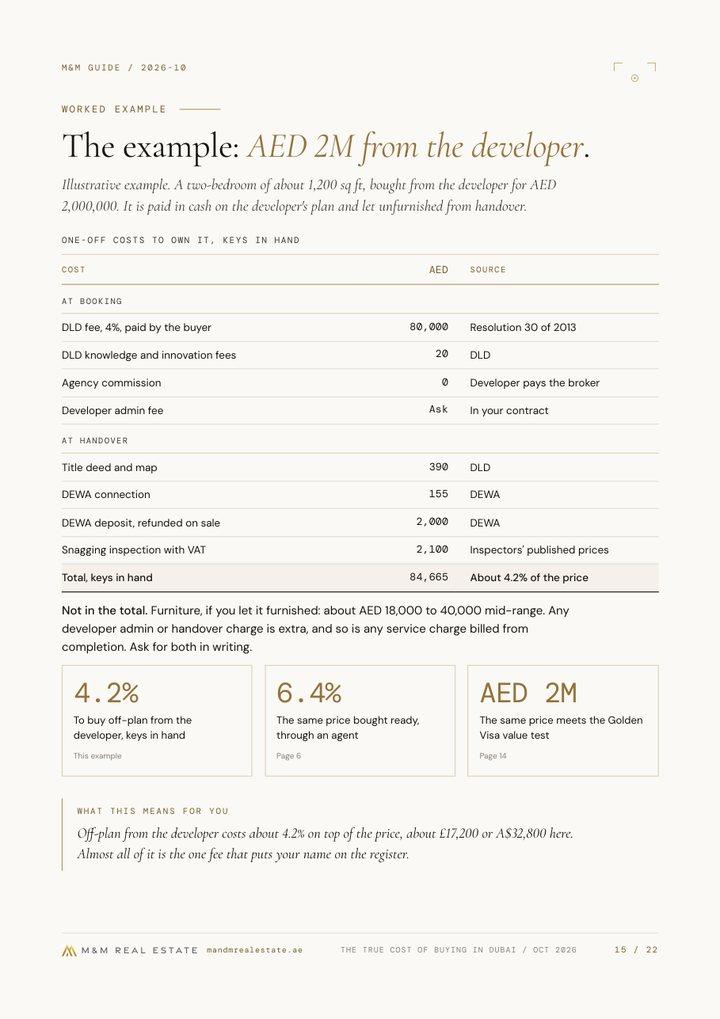
Put each offer on one timeline using the same assumed purchase date, handover date and unit price basis. Total the cash due at booking, during construction, at handover and afterwards so the first payment does not stand in for the whole cost.
| Cost to include | Where it belongs in your comparison |
|---|---|
| Purchase instalments | List each amount and contractual due date. |
| Purchase and registration charges | Keep these beside the purchase schedule, even when they are not instalments of the price. |
| Financing costs | Include expected bank and mortgage costs if you plan to borrow. |
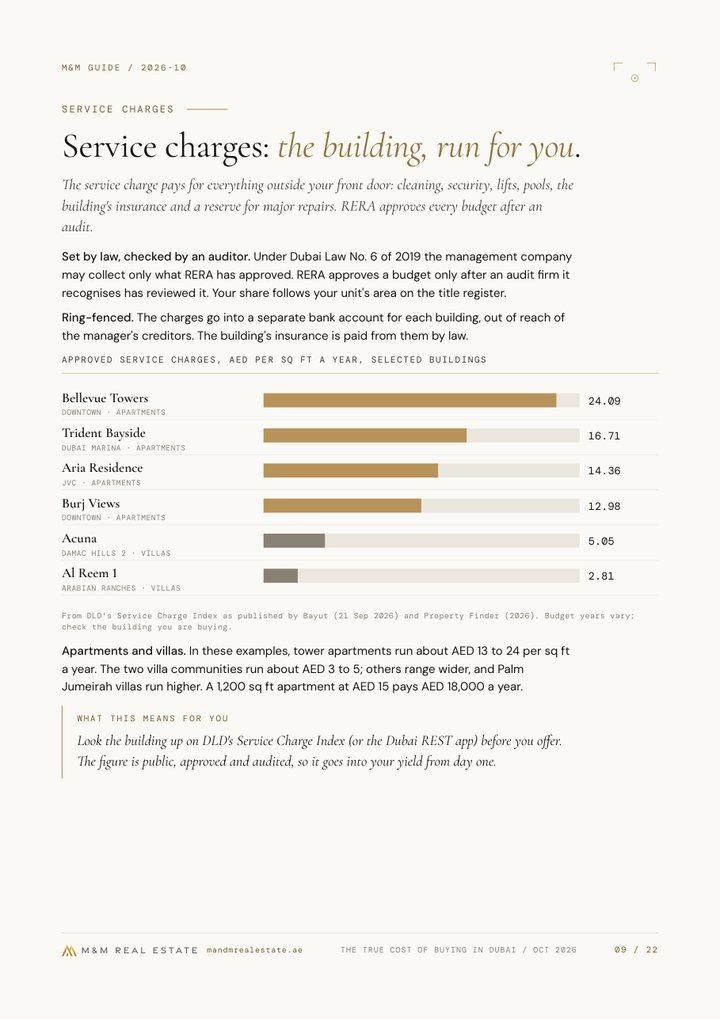
| Service charges | Budget recurring building costs for shared areas and services. |
| Furnishing and ownership costs | Allow for the cash needed to prepare and run the apartment. |
Compare incentives and payment flexibility against the full contractual price and every obligation. A smaller booking payment or longer schedule changes when you pay; it does not establish that the total cost is lower. Keep a separate reserve for purchase and ownership costs instead of committing all available funds to the first payment.
Hold the area and property type constant when comparing launch offers. For a location baseline, compare M&M’s Dubai area investment guide with its locations overview, with further detail on JVC, Dubai Hills Estate and Al Jaddaf Waterfront.
Keep the asset type consistent too. Villas and townhouses feature in M&M’s Bay Estate case, while commercial-property examples appear in its Yards Plaza office analysis and Yards Plaza Investment Case; use apartment launches as the basis for an apartment comparison.
Residency and tax are separate parts of the wider investment budget. For residency and tax questions, see M&M’s property Golden Visa guide and Dubai property tax explainer; the Dubai property crowdfunding guide describes a separate way to consider property exposure.
Match the schedule to your use of the apartment
An end-user should align construction and handover payments with savings and expected mortgage drawdown. Leave room for a delayed handover, lender conditions and costs due at transfer, since each can change when your cash is needed.
An investor should model rent from a realistic post-handover and occupancy date. Deduct service charges, furnishing and other running costs before comparing rental income with any instalments that remain.
Rent can start after an apartment is ready, while an instalment may fall due earlier or income may begin later than planned. To account for gross rent and costs, consult M&M’s Dubai rental yields guide; for wider context on future tenant demand, see its Dubai population analysis.
Model rent as uncertain in amount and start date. A forecast that covers one instalment may leave service charges, furnishing and other ownership costs unfunded, so base your plan on cash you can access without relying on rent arriving on time.
Stress-test the handover balance and delivery timeline
Calculate the handover balance in cash as well as a percentage of the price. Test whether you can pay it if mortgage approval is delayed, a lender’s valuation is lower than expected or your borrowing capacity changes.
Run a downside case that combines an income interruption with a later handover. Keep enough liquidity for scheduled instalments and ownership costs without depending on rent arriving on your preferred date.
The buyer still needs separate liquidity for due payments and a delayed handover. Developer track records can be reviewed in M&M’s Dubai developer profiles and developer comparison based on the public record.
If construction progress and a scheduled payment date appear out of step, use the contract’s milestone wording and request written clarification through the agreed process. Keep that response with your payment records before deciding how to meet the due date.
Use the sale agreement to confirm the obligations
Read the sale and purchase agreement (SPA) alongside the payment schedule. Check each due date, milestone definition, method of progress certification and the stated consequences of a missed payment.
Compare the SPA with the schedule presented at launch, then rely on the terms incorporated into the signed agreement. Verbal descriptions of flexibility do not replace the written payment obligations.
Before planning an early resale, establish the transfer conditions and how unpaid instalments will be handled. The SPA and the developer’s transfer process set out whether the existing buyer can transfer the contract and what must happen to the outstanding balance.
For each shortlisted plan, record the amount and date of every payment, the handover balance, costs outside the purchase price and the source of funds for each obligation.
This is general information, not tax or legal advice.
Conclusion: what to do before reserving
Before paying a booking amount, put the full schedule beside your available funds and mark the handover balance, purchase costs and ownership costs. Ask the developer to explain milestone evidence, the consequences of late payment and the process for any early transfer.
An M&M advisor will go through your budget, timeline and shortlist with you. Contact M&M Real Estate about the terms of a Dubai apartment launch and the cash flow each plan requires.
this article is general information and not tax, legal or financial advice, and returns are not guaranteed.
Can I make a lump-sum payment early if my payment plan is spread over several years?
Ask the developer to confirm how an early payment will be recorded and whether it replaces future instalments or remains as credit on your account. Keep the written account statement with your SPA documents.
What happens if a mortgage valuation is lower than the apartment’s agreed purchase price?
The lender may offer less finance than you planned, leaving a gap between the loan and the amount due under the SPA. A lower valuation does not automatically change the price agreed with the developer.
Can payment-plan terms differ between apartments in the same launch?
Yes, a developer may offer different terms for particular units or sales releases. Compare the unit-specific payment schedule and SPA, even when the apartments belong to the same launch.
Can I transfer an off-plan purchase to someone else before the final instalment is paid?
The transfer documents need to state whether the seller settles the remaining instalments or the new buyer accepts them. Obtain written confirmation of the transfer terms and the release of the original buyer’s obligations.
The true cost of buying in Dubai
Every fee from reservation to resale, with a worked example on an AED 2 million home. 22 pages. Free by email.