


Is it worth selling my UK buy-to-let to buy an investment property in Dubai? It can be, if the UK property’s net cash flow, tax position and future costs compare poorly with a Dubai property that suits your investment period. Dubai’s transfer fee is 4% of the sale value; the sale contract determines how the buyer and seller allocate that cost, so confirm who pays before comparing proceeds.
A decision rests on net proceeds, rent and your time horizon
- Work out what the UK sale would leave after the mortgage, selling costs, any early repayment charge and any capital gains tax.
- Compare net rental income for each property after vacancy, management, repairs, insurance, finance and tax.
- Include Dubai’s purchase costs and ongoing service charges in the amount of capital you commit.
- Assess ready and off-plan property separately. Their income timing, payment schedules and delivery risks differ.
- Test a sale scenario with no increase in property value, and account for the effect of converting AED income back into GBP.
- Ask an M&M advisor to review the UK sale estimate, tax position, budget and Dubai shortlist together.
Calculate the UK sale proceeds before setting a Dubai budget
The property’s expected sale price is only the start. Ask your solicitor and lender for a sale estimate that deducts the mortgage redemption balance, any early repayment charge, conveyancing and selling fees, and any capital gains tax due.
For a buyer who sells, the amount available for Dubai is the sale price less those costs. Keep a separate reserve for moving money, purchase costs and any period when the Dubai property earns no rent.
| UK sale calculation | Dubai purchase calculation |
|---|---|
| Sale price less mortgage redemption and any early repayment charge | Purchase price plus the DLD transfer fee and other transaction costs |
| Less selling fees and conveyancing costs | Include fit-out or furnishing costs where the property needs them before letting |
| Less any capital gains tax due | Include service charges, insurance and a cash reserve for vacancy and repairs |
Use actual quotes and your own tax calculation for each line. For UK investors considering Dubai, M&M’s investor resources provide background; an accountant or tax adviser can help calculate the UK disposal position.
Use the UK government’s Foreign, Commonwealth & Development Office guidance on buying property in the UAE as a starting point for the purchase process, not as a valuation or tailored legal opinion. Government guidance cannot assess your title, tenancy, tax position or the developer’s contract. The British Embassy cannot act as your lawyer, settle a private property dispute or recover money for you. Before committing, obtain a written UK tax calculation and an independent UAE legal review of the title and sale agreement, alongside the lender, solicitor and cost estimates used above.
A UK couple looking at Dubai from an apartment balcony is a useful reminder that the decision also involves where the capital will be held and how the property will be used.
Compare net rental income, not headline yields
Headline gross yields do not show the income an owner keeps. Compare the rent and costs for the specific UK property and Dubai unit you are considering.
Your own rent, vacancy periods, mortgage and running costs determine whether keeping your property produces useful cash flow.
For each property, calculate annual rent received after empty periods, letting or management fees, maintenance, insurance, finance costs and tax. For Dubai, include service charges, the annual building and community fees, as well as furnishing, repairs and tenant turnover.
For a like-for-like worked comparison, set out each property’s annual rent actually collected after vacancy, then subtract its management, repairs, insurance, finance and applicable tax; include Dubai service charges and purchase costs as well. Show the cash tied up separately from the income, and divide annual net income by that cash to compare the return on your committed capital. Convert Dubai income to GBP using an exchange-rate assumption that reflects your transfer timing. If Dubai produces more net income but ties up more capital, weigh that difference against its added costs, vacancy exposure and resale risk over your holding period. Use estimates for the specific units, not an area-wide headline yield.
A property manager can arrange tenant communication, rent collection, repairs and handovers while you live in the UK. Ask for the management agreement, its fee basis, what maintenance it can approve and how it reports rent and costs to you.
M&M’s rental options and tenant strategy explain the factors that shape Dubai rental income. The relevant comparison is the net income left after costs, not the advertised rent.
Jumeirah Village Circle can be part of a rental shortlist, but its area-level yield does not establish the return for an individual unit. Compare the building’s service charges, tenant demand and likely letting costs with the specific property you own in the UK.
UK tax residence can affect rent and a later sale
For an individual who owns Dubai real estate without a licence, UAE rules exclude rental income and gains from sale from corporate tax. A UK tax resident may still have UK tax to pay on Dubai rental income and a later gain, so Dubai’s local tax treatment does not settle the UK position.
Before selling, ask a UK tax adviser to assess capital gains tax using your purchase records, ownership history, improvement costs and current residence position. If you move out of the UK, review the Non-Resident Landlord Scheme and your reporting obligations with a tax adviser.
Estimate capital gains tax on the chargeable gain, not on the whole sale price. Start with the sale proceeds, deduct allowable acquisition and disposal costs and qualifying capital improvements, then account for any applicable reliefs, losses and ownership share. The tax rate depends on your circumstances and the rules applying when you sell, so there is no single rate to apply to every buy-to-let sale. Ask your adviser to show the gain calculation and the rate used, and check that both reflect current UK rules before deciding how much of the proceeds will be available to invest.
This is general information, not tax or legal advice.
M&M’s guide to Dubai property tax and UK considerations sets out why the investor’s home-country tax position belongs in the calculation. Keep records of rent, management fees, service charges, repairs, purchase costs and sale documents for your adviser.
Currency risk also affects the comparison. Sale proceeds may arrive in GBP, while Dubai purchase payments and rent are in AED; estimate the result in the currency in which you expect to spend the money, and consider when each payment is due.
Foreign capital is hesitating. The 3.9 million people inside the UAE have not. The asymmetry that defines 2026, and what it tells you to do about it.
Download free→Stress-test the Dubai resale case and market conditions
Dubai property prices can fall as well as rise. That changes the amount an owner might receive on resale, so test whether rent can carry the costs without relying on a future price increase.
Model a resale with no price growth, which leaves rental income carrying the investment before any sale gain.
Treat the market-index card below as a dated snapshot, not a forecast or a valuation for a specific unit. Before relying on it, check the period covered, index definition and underlying data on the named publisher’s page, then compare with relevant local transaction evidence. A broad residential index cannot establish an individual property’s achievable rent or resale price.
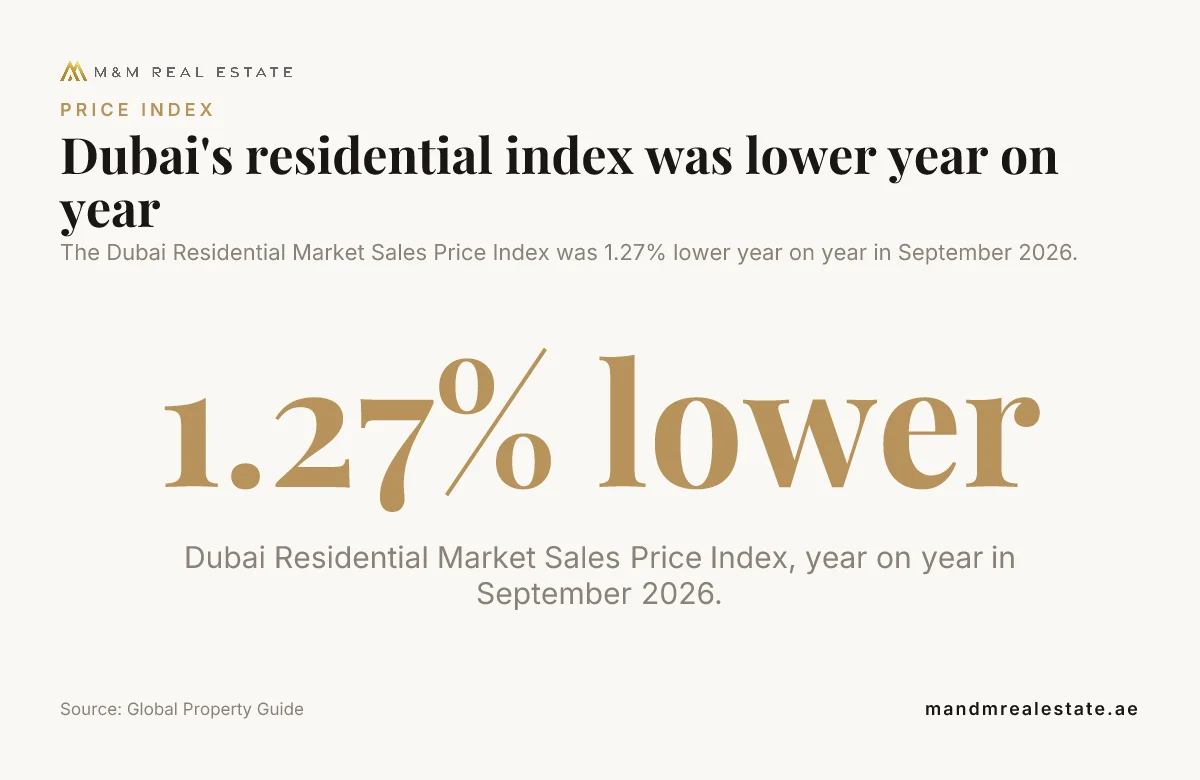
Source: Global Property Guide
Holding period changes the calculation. A short hold gives purchase costs, any rent-free period and resale costs less time to be offset by rental income. Over a longer period, the key questions include maintenance, tenant changes and how much capital remains tied up in the property.
If a Dubai property is leasehold for a fixed term, expiry does not automatically give the owner freehold title or a renewal. The outcome depends on the registered title, lease and applicable law; renewal, extension, compensation or rights to the building at expiry depend on the specific legal arrangement. Before buying, ask an independent UAE property lawyer to confirm the tenure, the term and the rights at expiry. Also check how the remaining term could affect resale or financing. Do not treat a fixed-term leasehold as equivalent to freehold ownership.
The distinction between ready and off-plan property is set out in M&M’s Dubai investment guide. The choice affects when rent can begin and when capital must be paid.
Choose an area and property that fit the investment plan
Start with the kind of tenant and rent you are targeting, then compare locations and buildings. Build the shortlist by comparing M&M’s area comparison for Dubai investors with the Al Jaddaf Waterfront location profile.
Area choice alone does not make a property a good buy. Compare the specific unit’s purchase cost, service charges, rent potential, tenant profile and resale audience. The locations directory also covers Dubai Hills Estate.
Property type matters too. Bay Estate by Nakheel is on Dubai Islands; M&M’s Bay Estate Investment Case covers the project.
The Yards Plaza is an office project, so its tenants, leasing market and operating costs differ from those of a residential buy-to-let. Review the Yards Plaza Investment Case and its project case page as a separate commercial-property option.
Dubai’s population is one factor investors may consider when assessing future rental demand. For context on a factor in future rental demand, consult M&M’s Dubai population analysis; a specific unit still depends on its location, costs and likely tenant base.
Off-plan property has a different cash-flow and delivery profile
With Dubai off-plan property, the buyer pays under a developer’s schedule before the home is ready to rent. A buyer who needs rent soon may prefer a completed property; an off-plan buyer needs enough capital for instalments and any amount due at handover.
Check the developer, project registration, escrow arrangements, payment milestones, completion terms and what the sales and purchase agreement says about delays and handover. Oqood is the DLD’s registration system for off-plan sales.
Use the DLD project status and escrow details as part of due diligence. Questions about delivery history and payment terms can be structured with M&M’s Dubai developer profiles and developer comparison.
For the off-plan process, see M&M’s Dubai off-plan property page; its note on a 30/70 payment plan explains how payment timing affects cash requirements. Compare every instalment with the date and amount of your available funds.
Ask UAE banks about non-resident eligibility, required documents and loan terms before committing.
For off-plan due diligence, an M&M advisor can review the developer, escrow, payment schedule and SPA with you. Ask the developer to identify the project’s registered status and the account to which each payment goes.
The Dubai Land Department issues a 10-year Golden Visa for qualifying property bought for AED 2M or more at the purchase price in the applicant’s own name. The visa route does not decide UK tax residence; consult M&M’s Dubai property Golden Visa guide and confirm mortgaged or off-plan property eligibility with the DLD.
Before you sell, build the full comparison
Is it worth selling my UK buy-to-let to buy an investment property in Dubai? Decide after you have the UK net proceeds, a property-level Dubai cost estimate, a tax review and an income calculation that includes vacancy, management and service charges.
Compare a ready property with any off-plan option, then test each against your expected holding period and a resale case with no price growth. For a smaller investment route than whole-property ownership, the Dubai real estate crowdfunding guide explains that alternative.
An M&M advisor will go through your budget, timeline and shortlist with you. contact page before you commit the proceeds of your UK sale.
Figures are past data from the sources named; this article is general information and not tax, legal or financial advice, and returns are not guaranteed.


Can I sell a UK buy-to-let while a tenant still lives there?
A sale can proceed with a tenant in place, subject to the tenancy agreement and the sale terms. Ask your solicitor to explain how the existing tenancy affects the buyer, completion arrangements and any vacant-possession requirement.
Should I convert all my UK sale proceeds into AED at once?
Set a currency plan around the dates when Dubai payments fall due and the GBP expenses you expect to keep paying. A bank or currency specialist can explain transfer costs and available conversion options for your payment schedule.
What records should I keep for UK tax reporting on Dubai rent?
Keep the purchase and completion documents, tenancy agreements, rent statements, management invoices, service-charge statements and repair records. A UK tax adviser can tell you which records support your own return and any later disposal calculation.
Can I buy a Dubai property through a UAE company?
A UAE company is one possible ownership route, but its legal, reporting and tax consequences depend on the investor’s circumstances. Discuss the structure with a lawyer and tax adviser before signing a purchase contract.


