


I’m emigrating from the Netherlands to Dubai, should I buy a home there or rent first? Rent first while your job, visa timing or likely length of stay remains uncertain. Buying becomes more compelling once you know where you want to live and a longer stay can absorb the costs of purchase and eventual resale. For the move itself, confirm your residence route and work permission first, then coordinate housing, healthcare, family needs, shipping and Dutch departure arrangements.
- Rent first if your relocation date, work plans or likely stay could change. Flexibility gives you time to learn how daily life works in Dubai.
- Compare total costs, including the deposit, DLD fee, mortgage costs, service charges, maintenance and resale expenses. A mortgage payment alone does not show the cost of ownership.
- Check the ownership area and your residency route separately. Foreign buyers can own in designated freehold areas, while property ownership and permission to live or work in the UAE are separate matters.
- Try the area in person before making a long commitment. Commute times, transport, heat and everyday services can change how suitable a home feels.
- Include the Dutch side of the move in your budget. Dutch tax residency, a retained home, pension arrangements and euro-to-AED movements all affect the decision.
Decide how settled you are before committing
Rent first if your move date, employment or visa timing is uncertain. A rental gives you somewhere to live while those plans settle, without tying a large share of your capital to a home you may soon want to leave.
Buying becomes more compelling when you expect to stay long enough for the cost of ownership and eventual resale to compare well with rent over the same period. Test a shorter stay and a longer stay. A recent rise or fall in prices cannot tell you how long you will stay or what your eventual sale will bring.
Include employer-provided housing in the comparison. Ask how long the home or housing allowance lasts, which costs it covers, and whether it limits your choice of area or property type.
Dubai’s growth and development plans form part of the city’s changing context, but they do not settle an individual rent-versus-buy decision. M&M’s article on Dubai population growth gives further context for investors considering the city.
Write down the move date, expected stay and employer support, then test the decision against both a shorter and a longer timeline.
Compare rent with the full cost of owning
Compare the cost of renting with the full cost of buying the same kind of home for the same period. The ownership budget includes the purchase price, transaction and registration costs, mortgage interest and fees, service charges, maintenance, insurance and the costs of selling.
Include transfer and registration costs alongside the deposit when calculating the cash needed to complete.
Include mortgage registration and trustee office fees in your purchase budget.
Include the opportunity cost of the deposit and other purchase funds. Capital tied up in a home is unavailable for relocation expenses, savings or other plans, so compare ownership with what those funds would otherwise support.
Include tenancy registration, utilities and any temporary accommodation costs in the rental budget.
For a like-for-like comparison, include employer housing support in the period it applies. Estimate a break-even point for more than one expected stay, and adjust the calculation for financing terms, service charges, maintenance, resale costs and possible EUR-to-AED movements. The result is a planning estimate, not a promised outcome.
For a like-for-like check, total the rent payments, tenancy registration, utilities and temporary accommodation for your expected stay. Compare that with purchase and registration costs, financing, service charges, maintenance and selling costs, allowing for any employer housing support in either case. Treat sale proceeds as an estimate, not a certainty; if buying only looks less costly under an optimistic resale assumption or a longer stay, test a less favourable scenario too.
Property crowdfunding offers a way some investors consider property exposure separately from a home purchase decision; read M&M’s guide to property crowdfunding in Dubai. The
Build one rent budget and one ownership budget for each expected stay before deciding which option fits your move.
Understand where foreign buyers can own and what ownership means
Check whether the area and title structure allow you to own the property. The right to own a property and permission to live or work in the UAE are separate decisions, so review the title area and immigration route independently.
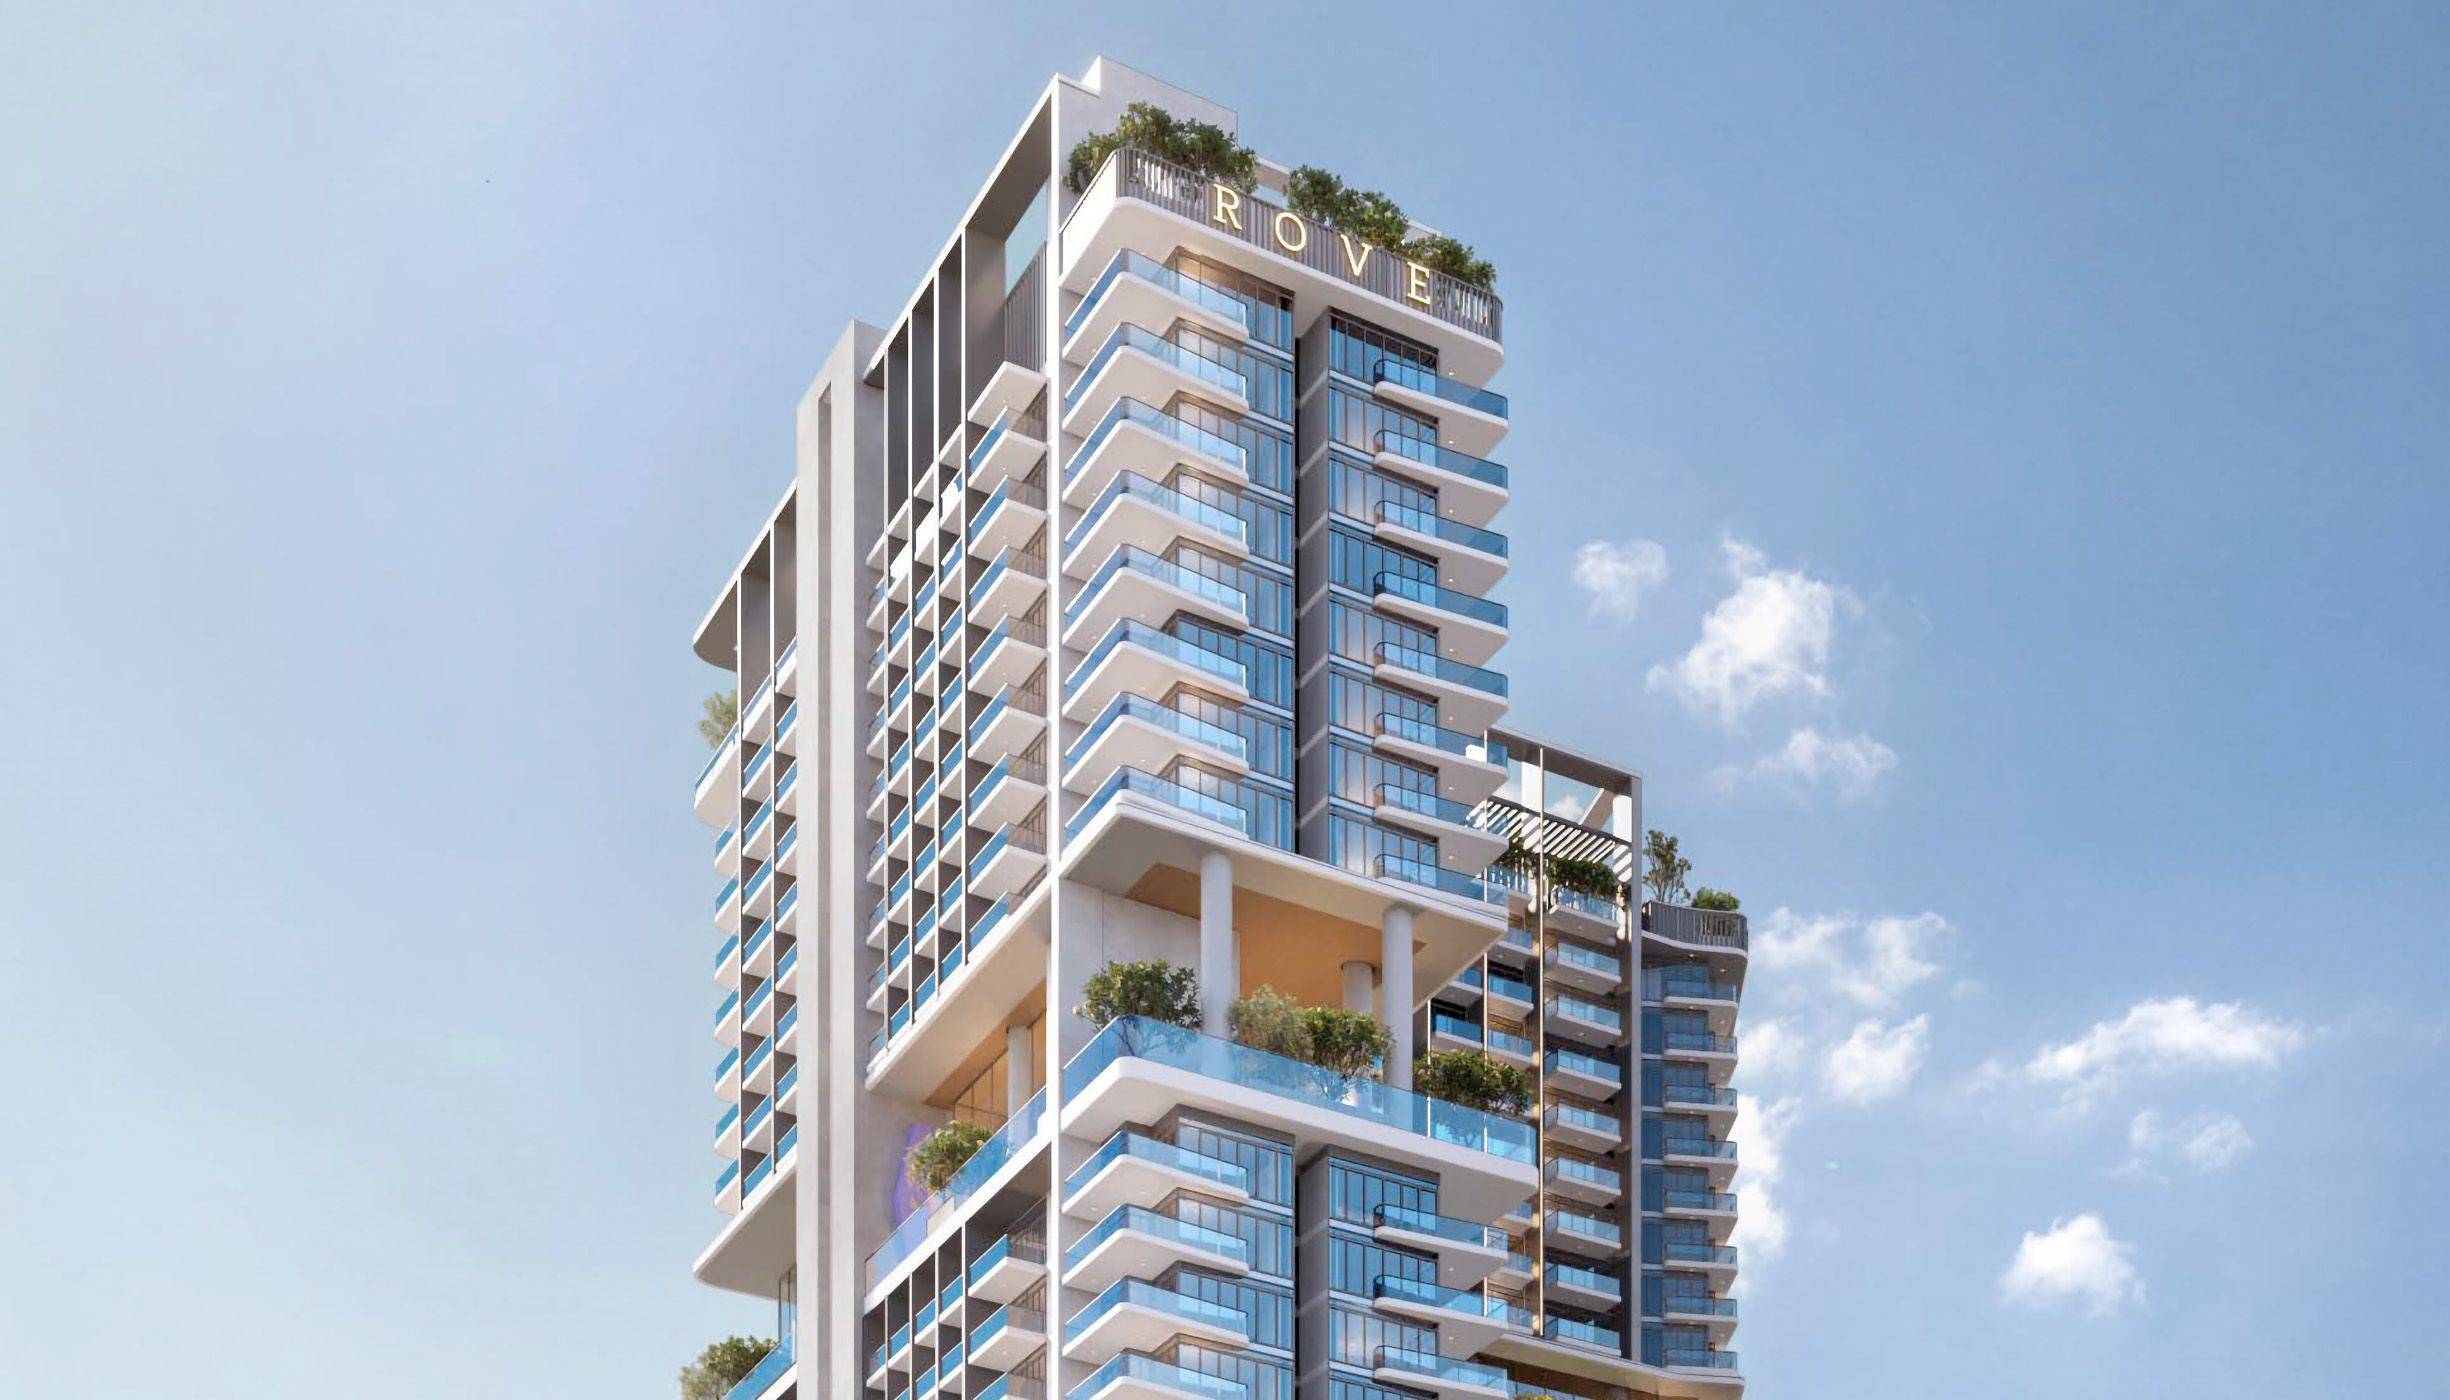
The Rove Home Marasi Drive project is one option to assess against your intended move date and home requirements.
For a family considering how property and residence fit together, M&M’s
For a comparison between a home and an investment purchase, read M&M’s Bay Estate by Nakheel Investment Case. Keep the decision about where to live distinct from any decision to buy property for investment.
If you plan to use a mortgage, compare lender eligibility, rates, fees and currency exposure.
The
Compare the freehold title, residency route and financing terms for each shortlisted property before you pay a deposit.
Use a temporary rental to test everyday life
Plan temporary accommodation around your arrival, visa timing and property-search schedule. A short initial stay gives you time to visit homes in person and learn which areas work for your household before you sign a longer tenancy.
For a long-term rental, read the tenancy contract carefully and arrange Ejari, the Dubai tenancy registration. Set up DEWA, Dubai Electricity and Water Authority, for utilities, and include the housing fee on the DEWA bill in your monthly budget.
Compare temporary accommodation with a standard tenancy on total cost and practical terms. Furnishing, utility charges, length of stay and the ability to change dates can all affect what the short-term option costs.
If your employer provides a home or housing allowance, ask for the end date and conditions in writing before you choose a rental. To organise questions for the move and property search, use M&M’s Dubai investment resources.
Set your temporary stay dates around your arrival and planned viewings, then decide whether a longer lease suits the area you have tested.
Foreign capital is hesitating. The 3.9 million people inside the UAE have not. The asymmetry that defines 2026, and what it tells you to do about it.
Download free→Choose an area by testing your routine, not just the property
Test the commute at the times you expect to travel. Check access to work, schools and other regular destinations, since the route and daily route can change how suitable a home feels.
Visit shortlisted areas at different times of day. Consider heat, walking distances, public transport, parking and access to groceries, healthcare and other everyday services.
Compare apartments, townhouses and villas against your household’s space needs and willingness to manage upkeep. Service charges and community arrangements also vary by building and property type, so include them when comparing homes.
Build your shortlist with M&M’s Dubai area guides. For a more specific comparison, read about Al Jaddaf Waterfront and Dubai Hills Estate.
Renting in a promising area first can show whether its routine suits you before you commit capital to a purchase.
Visit your preferred area during a normal working day and at the times you expect to travel before choosing a long-term home.
Carry out buyer checks before signing or paying
Check the title and ownership position, the agent’s authority to act and the purchase contract. Arrange an independent legal review before signing or paying a deposit, whether you view the home in person or buy remotely.
For a completed home, inspect the physical condition and ask for the service charge details and likely maintenance obligations. A building’s ongoing costs affect the ownership budget after completion, so include them in your comparison with rent.
For an off-plan property, read the sale and purchase agreement, payment schedule and completion terms. Check the project’s escrow arrangement and verify the project and developer before committing.
M&M’s
For developer checks, start with M&M’s Dubai property developer profiles. For payment schedules, the 30/70 payment plan analysis explains how a plan affects the timing of payments.
When buying remotely, arrange independent checks of the property, documents and parties involved, and keep the results in writing.
Complete title, contract, developer and payment checks before you sign or transfer funds.
Prepare the move from the Netherlands
Before booking a shipment, make an inventory and get written quotes that spell out packing, transport, customs clearance, delivery, insurance and storage. Ask the mover which documents are needed and check restrictions on items you plan to bring. Keep passports, residence paperwork, prescriptions and essential belongings accessible rather than packed with the main shipment, and coordinate delivery with your confirmed accommodation.
Ask your Dutch municipality about deregistering from the Personal Records Database (BRP) and the timing that applies to your move. Notify relevant tax, insurance, banking, pension and utility providers, and ask your Dutch health insurer when your cover ends. Deregistration does not by itself settle your tax position or insurance arrangements, so confirm those separately with the municipality, insurer and a qualified adviser.
Plan the Dutch tax and financial side of the move
Discuss how emigration may affect Dutch tax residency with a qualified tax adviser. If you keep a Dutch home or rent it out, include its ownership, use and income in the discussion alongside your planned Dubai purchase.
Ask your adviser how the rules apply to a home you retain, based on your ownership and plans for the property.
Review savings, pension arrangements and continuing Dutch financial obligations alongside the cash needed for a Dubai purchase. If you earn or hold money in euros while your housing costs are in AED, model how currency movements could change the funds available for deposits, mortgage payments and ongoing costs.
Your home country may still tax rental income or gains. Ask an adviser to review your Dutch tax residency before deciding how to hold or finance a home.
This is general information, not tax or legal advice.
M&M Real Estate’s page for investing in Dubai from the Netherlands addresses Dutch investor questions. For further context on tax on Dubai property, read M&M’s tax overview.
Prepare a list of Dutch assets, income, pension arrangements and continuing costs to discuss with a cross-border tax adviser.
See also: Off Plan Properties in Dubai, The Yards Plaza by BEYOND, City of Arabia Offices, The Yards Plaza by BEYOND, City of Arabia Offices, M&M.
What to do before you move
Set your likely stay period, confirm what your employer will cover and compare rent with ownership costs under shorter and longer scenarios. Then shortlist areas, test the commute and daily routine, and review Dutch tax and currency questions with qualified advisers before committing capital.
If you are still asking, I’m emigrating from the Netherlands to Dubai, should I buy a home there or rent first?, rent first when your plans or area choice remain uncertain. Speak with an M&M advisor to review your budget, timeline and shortlist.
This article is general information and not tax, legal or financial advice.


Can I keep my Dutch home after moving to Dubai?
If you keep a home in the Netherlands, arrange who will manage it while you are abroad and keep records of any rental income, repairs and property documents.
Can I buy a Dubai property jointly with my spouse?
If you plan a joint purchase, agree the ownership shares and mortgage responsibilities before signing. Confirm any residence-route eligibility with the relevant authority.
Can I sell my Dubai home if I later move away?
Include any outstanding mortgage and expected selling costs in your plan for a future sale.
What should I do if my relocation date changes after I have arranged accommodation?
Contact the accommodation provider or landlord as soon as the date changes and request any revised dates or costs in writing. Keep a backup stay option available if the new arrival date falls outside the agreed booking or tenancy period.
Why do people choose to live in Dubai?
People may choose Dubai for work, climate, services or personal reasons; priorities vary.


