


If you are asking, I’m thinking about retiring from the UK to Dubai, is buying a property there sensible? It can be sensible when the home fits your retirement budget, residence plan and expected length of stay. Retirement in Dubai can be practical if your income or savings cover ongoing costs, you can arrange suitable healthcare and qualify for a residence route; buying is not required. Renting first gives you time to test Dubai’s climate, neighbourhoods and daily routine before you commit capital.
- Rent first if you have not experienced Dubai through a full season. Compare the cost and flexibility of renting with the full cost of owning.
- Foreign nationals can buy freehold property in designated areas. Explore Dubai’s locations by their fit with everyday needs as well as investment aims.
- Budget for the purchase and ongoing costs, including the DLD transfer fee, service charges, maintenance and any mortgage expenses.
- Compare completed homes with off-plan purchases by inspection, contract terms, construction progress and the date you need to move.
- A property purchase does not itself give you permission to live in the UAE. Read the Golden Visa property route separately from the property decision.
Decide whether to buy now or rent first
If you have not lived in Dubai through a full season, rent first. A trial stay lets you assess the heat, healthcare access, transport, shops and the pace of daily life before you tie up a large part of your savings in a home.
Buying may suit a retiree who expects to stay for long enough to justify the purchase and sale costs, and who wants control over their home. Renting keeps more options open if health needs, family plans or a preferred neighbourhood change.
Set out the property’s purpose before comparing homes: a place to live, a source of rental income, or both. M&M Real Estate’s Advisory, free investor guide, legal setup and compliance support for UK investors can help define that objective, including whether the priority is income, residency or diversification.
If you will let the home while you are away, work out net income after service charges, maintenance, management fees and periods without a tenant. A gross, asking-based rental yield is a market measure, not the amount an owner receives after costs.
Use a written budget, a time horizon and a plan for the property to compare buying with renting. M&M’s Dubai population analysis can provide market context, while your own decision should rest on the location and costs of the property you would actually own.
Understand ownership rights and choose a place to live
UK citizens can buy property in Dubai without living in the UAE, subject to the property’s ownership rules and the transaction requirements. Foreign nationals can buy freehold property in designated freehold areas, where the buyer owns the title; leasehold gives rights for the term recorded in the lease.
Choose a location around daily needs: access to healthcare, shops, public transport, community facilities and the airport. To structure comparisons, use M&M’s area analysis; the Dubai Hills community and Al Jaddaf Waterfront are examples to assess against your own routine.
If you intend to let the home, assess its tenant base and likely net income separately from its suitability for your own retirement. A location that rents well may not give you the healthcare access or daily facilities you want.
Ownership and residence are separate decisions. A home purchase does not itself grant permission to live in the UAE, so plan the visa route alongside the choice of property.
Build a retirement budget beyond the purchase price
The Dubai Land Department transfer fee is 4% of the sale price. How that fee is allocated between seller and buyer depends on the agreement and transaction, so confirm the split and related charges before signing.
| Budget line | Include |
|---|---|
| Purchase | DLD transfer fee, registration and trustee charges, agency fees, legal advice, and mortgage arrangement or valuation costs if borrowing. |
| Ownership | Service charges, utilities, insurance, maintenance and property management. These costs continue to affect the budget when the property is empty. |
| Retirement | Healthcare cover, UK travel, furnishing, possible mobility or care needs, and a reserve for repairs. |
If you rent the property out, deduct service charges, management, repairs and vacancy from the expected rent before deciding whether the income supports your retirement plan. For UK buyers considering cross-border property costs, M&M’s investor resources include relevant material.
Model your budget in both GBP and AED if your pension or savings are in sterling and your property costs are in dirhams. Exchange rates can change the sterling cost of an AED payment and the GBP value of any rent you receive.
For a mortgage, compare the deposit, loan-to-value, rate, term and repayment schedule with your retirement income and cash reserve.
Compare completed homes with off-plan purchases
A completed home can be inspected before purchase and may be occupied sooner. Review its condition, building management, service charges and title, and check that the home suits your mobility and care needs.
An off-plan property is bought before it is built. Review the developer, payment schedule, escrow account, contract terms, construction milestones and handover provisions; an escrow account holds project payments, with release governed by the applicable rules.
Read the Sales Purchase Agreement carefully. Off-plan sales are recorded on Oqood, the DLD’s off-plan registration; ready properties transfer at the DLD on completion.
Project delivery and track records are key checks: use M&M’s Dubai off-plan property listings to understand the type of purchase being considered, and its developer profiles to structure those checks. A retirement timeline that depends on moving into a specific home needs room for construction and handover changes.
The amount due at handover belongs in the comparison too; include M&M’s payment plan analysis when comparing payment schedules. For project-level reading, see the Bay Estate by Nakheel Investment Case and the Emaar and DAMAC developer comparison.
As commercial property, M&M’s The Yards Plaza by BEYOND case and its Investment Case concern an income asset with a different role from a retirement home. Crowdfunding is a separate route to consider if full ownership concentrates too much capital in one asset; M&M’s overview of Dubai property crowdfunding describes it.
What thousands of high-net-worth British residents are doing right now, the forces pushing them, and what Dubai offers in 2026.
Download free→Check residence eligibility separately from buying
A property purchase does not automatically give the owner UAE residence. Check the eligibility rules, application process and renewal conditions for the route you plan to use with the relevant UAE authority.
The Dubai Land Department states that a retired visa applicant must be over 55 years old. Age alone does not establish eligibility for that route.
The applicant must be over 55 years old.
Source: Dubai Land Department.
The Dubai Land Department issues a 10-year Golden Visa for qualifying property purchased for AED 2M or more in the applicant’s own name. For the property route, M&M’s Golden Visa information describes the requirements; the purchase price, ownership details and application requirements determine whether an application qualifies.
For mortgaged or off-plan property, confirm eligibility with the DLD. Build a plan that remains affordable if an application is refused or renewal conditions change.
Account for UK tax, pensions and currency exposure
Assess UK tax residence under HMRC’s Statutory Residence Test. Moving abroad or buying property overseas does not by itself end UK tax obligations.
If you remain UK tax-resident, overseas rental income and gains may need to be reported and may be taxable under UK rules. UAE personal income tax does not apply to rent or property gains, while your UK position depends on your tax residence and circumstances.
Before changing pension arrangements or transferring a pension, ask advisers who understand both UK and UAE rules to model the timing and tax effects. Model rental income, property expenses and retirement income in the currencies in which they arise, because a currency movement can alter both affordability and the amount received in GBP.
This is general information, not tax or legal advice.
Plan for inheritance and make a decision you can live with
Coordinate wills and succession planning across the UK and UAE. A qualified lawyer in each jurisdiction can explain how the property’s ownership and title affect inheritance.
Discuss personal ownership, joint ownership and any company structure with legal advisers in both countries. M&M’s UK investor service describes legal setup support for ownership held personally or through a UAE company, coordinated with UK-qualified solicitors and UAE legal partners.
Test the decision against a return to the UK, a period when the property cannot be let, higher ongoing costs and a sale at a less favourable time. A home purchase works when its purpose, full cost, residence route and exit plan fit together.
Before you proceed, write down your budget, the date you want to move, the visa route you plan to use and the maximum ongoing cost you can carry. An M&M advisor can go through your budget, timeline and shortlist with you. Speak with an M&M advisor.
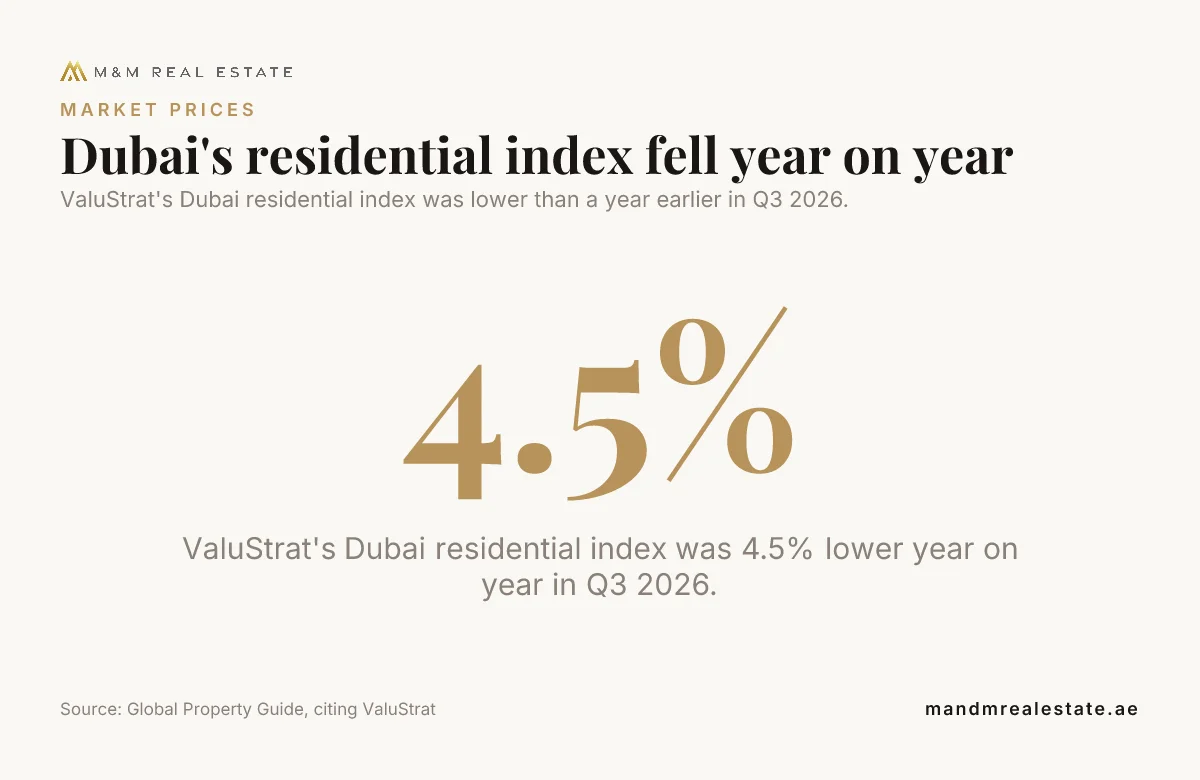
Source: Global Property Guide, citing ValuStrat
What to do before you commit
If you are still asking, I’m thinking about retiring from the UK to Dubai, is buying a property there sensible?, decide first whether the property is a home, an income asset or both. Then test the full cost, residence route, UK tax position and exit plan against your retirement income.
If you have not lived in Dubai through a full season, rent first and compare neighbourhoods through your normal routine. Buy when the property and the wider retirement plan make sense together.
Figures are past data from the sources named; this article is general information and not tax, legal or financial advice, and returns are not guaranteed.


What happens to a Dubai property after a 99-year lease ends?
The lease and registered title set out the rights that apply at expiry, including any renewal terms. Have a UAE property lawyer review those documents before purchase so the end-of-term position is clear.
Is the UK a better place to live than Dubai for retirement?
There is no single answer for every retiree: family support, familiar services, healthcare arrangements, climate and residence eligibility all affect the choice. Compare the life you expect in each place, including the costs of travel and care.
Can I sell my Dubai property and return to the UK if my plans change?
A sale can release capital for a move, with the timing and proceeds depending on the property, market conditions and completion of the transfer. Keep a separate return plan for the period before a sale completes.
Can I own a Dubai property jointly with my spouse?
Spouses can hold property jointly, with ownership recorded on the title. Agree how each person’s share, decision-making and inheritance will work before signing the purchase documents.


